Seoul Chipmakers Face Margin Pressure as Chinese Foundries Scale Conventional Memory
PwC report warns South Korean semiconductor firms to prioritise profitability over volume as CXMT and YMTC expand in legacy nodes and packaging
Profitability Over Volume
South Korean semiconductor manufacturers are being advised to shore up margins rather than chase shipment volume, as Chinese memory and foundry players accelerate their footprint in segments once dominated by Seoul. Samil PwC, the South Korean member firm of the global consultancy, released guidance on 26 October 2026 pointing to three battlegrounds where Chinese competition will intensify soonest: conventional memory chips, mature-node fabrication, and back-end assembly and test services.
The consultancy's intervention reflects a recalibration underway in Seoul's chip industry. For two decades South Korean conglomerates built market power by scaling leading-edge DRAM and NAND lines faster than rivals could match capital expenditure or process complexity. That playbook now confronts a different challenge. Chinese manufacturers are not racing to the smallest transistor geometries; instead they are flooding capacity into proven nodes where equipment export controls are less restrictive and where demand from automotive, industrial and consumer electronics remains robust.
The Chinese Capacity Build
At Opentechwire, we have tracked the expansion of Changxin Memory Technologies and Yangtze Memory Technologies Corporation over the past three years. CXMT has brought multiple DRAM fabrication modules online in Hefei, targeting DDR4 and LPDDR4X specifications that still account for the majority of unit shipments in smartphones and entry-level computing. YMTC has pushed 3D NAND production in Wuhan, reaching layer counts that close the technical gap with incumbent suppliers even as United States export rules constrain access to the most advanced deposition and etch tools.
Both companies benefit from patient provincial and central government capital, which tolerates longer payback periods than public equity markets typically allow. That financial structure lets Chinese fabs underprice South Korean and Taiwanese output in commodity-grade memory, compressing spot prices and squeezing gross margins across the supply base. The effect cascades through the value chain: module makers, distributors and OEMs all reset their cost assumptions when a new source offers equivalent specification at a lower bill of materials.
Packaging and test capacity is following a similar trajectory. Outsourced assembly and test houses in Jiangsu and Sichuan provinces have added wire-bond and flip-chip lines calibrated for mature logic and memory die. These facilities do not yet handle the most advanced chiplet interconnects or heterogeneous integration, but they absorb work that would otherwise flow to subcontractors in South Korea or Taiwan, eroding utilisation rates and pricing power for established players.
Seoul's Strategic Response
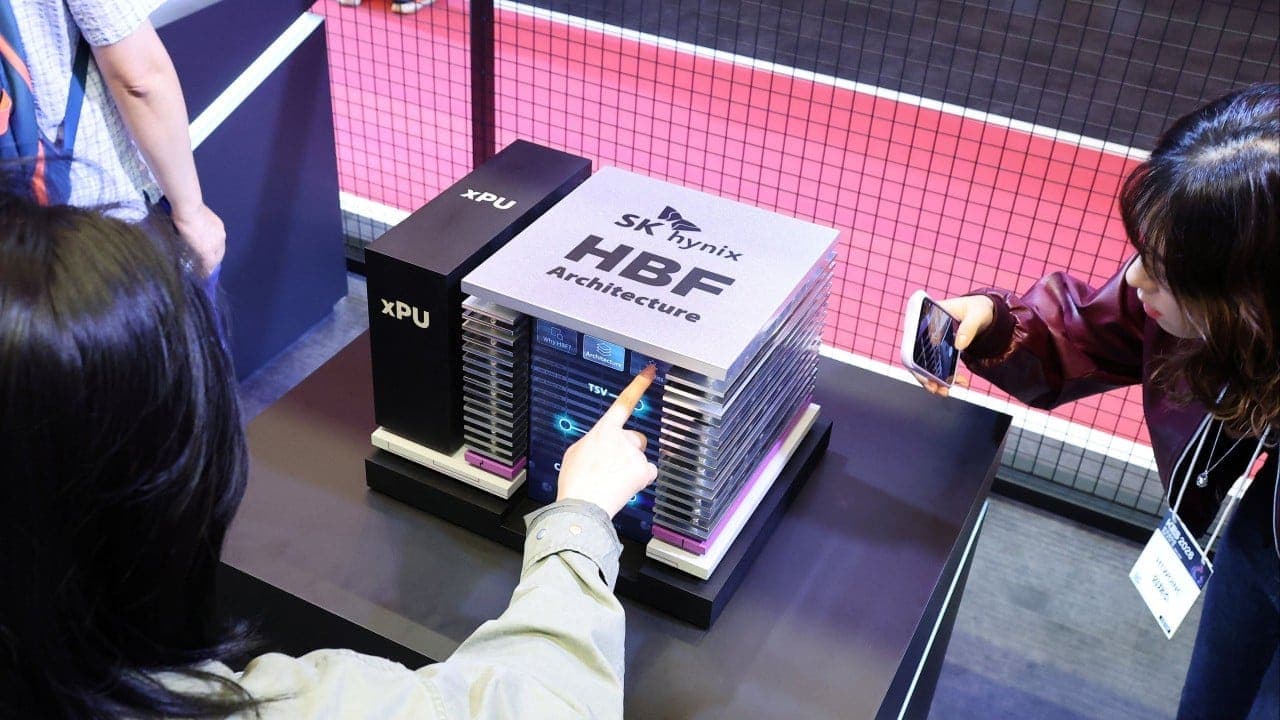
The PwC report stops short of recommending a retreat from any product category. Instead it urges South Korean firms to segment their portfolios more sharply, reserving high-margin leading-edge capacity for customers willing to pay for performance, power efficiency and supply assurance, while either exiting or automating lines that compete primarily on price. In practice that means accelerating depreciation on older 10-nanometre-class DRAM fabs and 96-layer NAND facilities, redeploying cleanroom space for next-generation high-bandwidth memory or compute-express-link attached memory modules that command better returns.
It also implies closer collaboration with hyperscale cloud providers and automotive tier-ones, locking in long-term agreements that guarantee offtake volume in exchange for co-investment in process customisation. Such partnerships insulate a portion of revenue from spot-market volatility and create switching costs that Chinese entrants cannot easily replicate. The consultancy highlights examples in which South Korean memory makers have embedded engineering teams at customer data centres, tuning DRAM refresh rates and error-correction algorithms to specific workloads. That level of integration takes years to build and is difficult to commoditise.
Policy and Export-Control Context
South Korea's semiconductor policy has historically balanced industrial promotion with alliance commitments to Washington. The country participates in multilateral export-control regimes that restrict shipment of extreme-ultraviolet lithography systems and advanced deposition tools to Chinese fabs. Those controls slow but do not halt Chinese progress in mature nodes, which rely on deep-ultraviolet steppers and older etch platforms that remain exportable or have already been installed.
Seoul's own subsidy programmes, including tax credits for fab construction and research grants for materials development, are being recalibrated to emphasise differentiation rather than raw capacity. The Ministry of Trade, Industry and Energy has signalled that future support will favour projects in areas such as chiplet standards, advanced packaging for artificial-intelligence accelerators, and memory architectures optimised for inference workloads. The aim is to steer investment towards segments where Chinese rivals face steeper technical or ecosystem barriers.
Export-control enforcement remains a friction point. South Korean equipment suppliers and chemical companies serve customers in China, and tighter restrictions risk revenue loss without necessarily slowing Chinese capability if alternative suppliers emerge or if indigenous substitution succeeds. The PwC report does not wade into that policy debate, but its emphasis on profitability implicitly acknowledges that volume growth in legacy segments is no longer a viable anchor for shareholder returns.
Implications for the Regional Supply Chain
The competitive shift has ramifications beyond corporate profit-and-loss statements. If Chinese memory and foundry output continues to grow in mature nodes, global buyers gain supply redundancy, reducing the leverage that any single geography holds over pricing or allocation during shortage cycles. That redundancy can stabilise electronics supply chains, but it also means that South Korean and Taiwanese producers must work harder to justify price premiums.
Packaging and test is particularly sensitive. Much of the world's semiconductor assembly capacity sits in Southeast Asia, operated by subcontractors that serve multiple chip designers and integrated device manufacturers. As Chinese OSAT providers scale, they offer a lower-cost alternative for companies willing to navigate export-compliance paperwork and manage longer logistics chains. South Korean chipmakers that own captive assembly lines face a choice: compete on cost by automating and consolidating, or differentiate by offering advanced packaging capabilities such as through-silicon vias, fan-out wafer-level packaging, or hybrid bonding that Chinese houses cannot yet match at volume.
The PwC guidance arrives at a moment when memory prices have begun to stabilise after two years of cyclical downturn. Inventory correction in PC and smartphone channels has run its course, and demand for DRAM tied to generative-AI training clusters is lifting high-bandwidth memory ASPs. But conventional DDR4 and mid-tier NAND pricing remains under pressure, and Chinese supply is a persistent source of that pressure. South Korean executives are being advised to treat the current price recovery as an opportunity to exit marginal product lines rather than to reinvest in capacity that will face even stiffer competition in the next cycle.
A Margin-First Playbook
At the operational level, a margin-first strategy requires discipline in capital allocation, faster process transitions, and tighter collaboration with customers who value performance over cost. It also requires a willingness to cede unit-share leadership in segments where returns no longer justify the invested capital. For an industry that has historically measured success by fab utilisation and gigabyte shipments, that cultural shift is non-trivial.
The consultancy's message is that South Korean chipmakers retain advantages in process technology, ecosystem relationships, and manufacturing know-how, but that those advantages will not automatically translate into financial outperformance if management teams continue to optimise for volume in commoditising markets. Chinese competitors have demonstrated that they can close technical gaps in mature nodes faster than many observers expected, and that patient capital allows them to sustain pricing that pressures incumbents.
Whether Seoul's semiconductor leaders heed the advice will become visible in the next round of capital-expenditure disclosures and in the mix of products that come out of their fabs. The stakes are high: memory and foundry operations account for a significant share of South Korea's exports and employment, and any erosion in profitability eventually constrains the resources available for next-generation research and development. The competition from China is not a future scenario; it is already reshaping spot prices, contract negotiations, and the return on invested capital across Asia's chip industry.