Series A Fundraising Faces Market Froth and Looming Correction
Venture investors warn of inflated metrics and unusual term structures as founders navigate one of the most challenging fundraising environments in decades
The New Reality of Early-Stage Capital
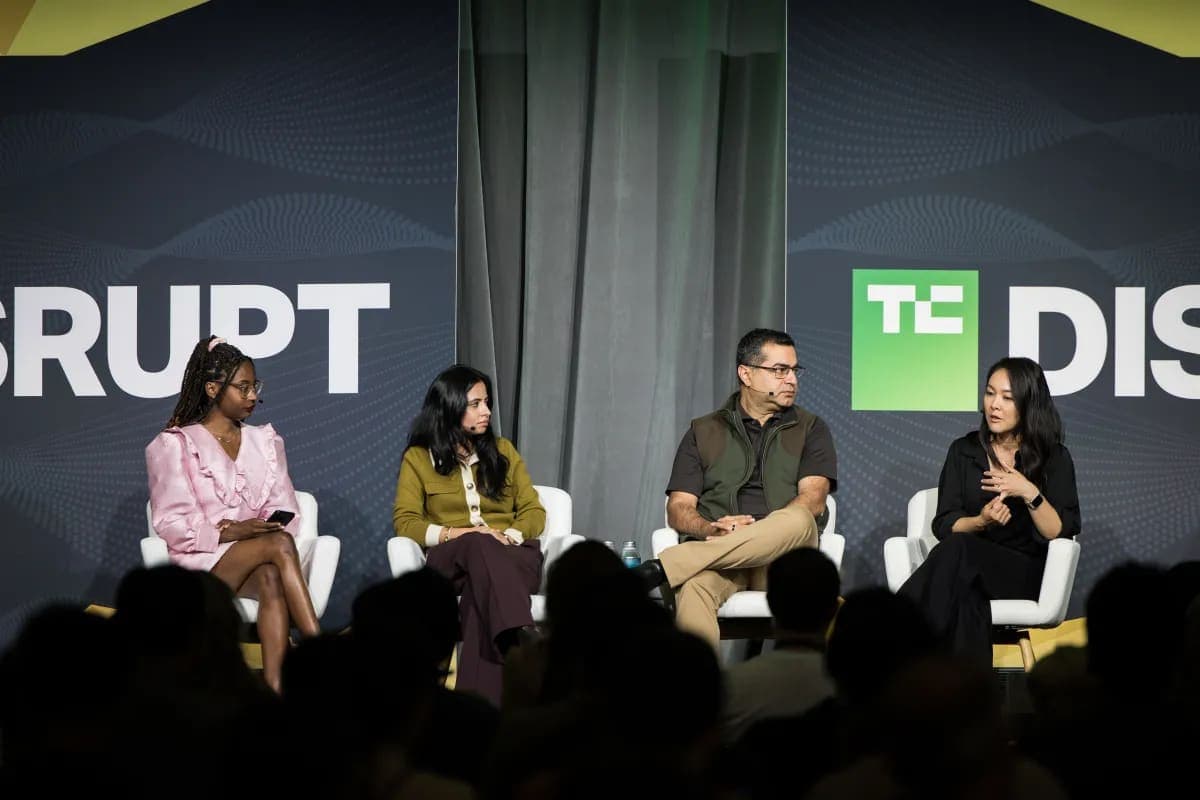
Shailendra Singh has spent two decades watching venture cycles, and the current Series A environment ranks among the most dysfunctional he has witnessed. Speaking at a recent founder event, the Peak XV managing director described a market where companies routinely negotiate three different price points simultaneously for the same round - a phenomenon he calls a clear indicator of excess.
The problem extends beyond pricing mechanics. Singh warned that money flooding into artificial intelligence has created inflated revenue figures that justify valuations disconnected from underlying fundamentals. His forecast: a correction could arrive as early as 2027.
Jahanvi Sardana, a partner at Index Ventures, coined a term for the structural oddity defining today's deals: "tranchopalooza." Rounds are being carved into separate chunks, each with distinct terms, as investors hedge their exposure whilst founders scramble to close capital at any structure that works.
At Opentechwire, we have tracked Series A data across Southeast Asia, India, and Greater China for the past eighteen months. The patterns Singh and Sardana describe are not confined to Silicon Valley. Founders in Bengaluru, Singapore, and Seoul report similar term-sheet fragmentation, with lead investors often syndicating only partial commitments and leaving the remainder to be filled at different valuations weeks or months later.
What Investors Actually Want to See
Despite the chaos, three criteria remain consistent across top-tier firms when evaluating Series A candidates.
First, a compelling narrative about market opportunity and founder resilience. Janelle Teng Wade, a partner at Bessemer, emphasised that the ability to recruit exceptional talent signals both vision and execution capability. Singh echoed this, noting that founders who can attract senior engineers or operators from incumbent platforms demonstrate credibility that slides cannot convey.
Second, sector alignment matters more than ever. Teng Wade pointed to capital concentrating in defence technology, robotics, and AI infrastructure. Foundational model companies are moving toward vertical integration - building more of the stack in-house rather than relying on third-party providers - but opportunities remain for specialised players. Neo-clouds that lease AI compute capacity and neo-labs focused on model research continue to attract institutional interest.
Third, financial metrics still carry weight, though the goalposts have shifted. The traditional benchmarks - one million to two million dollars in annual recurring revenue, 15 to 20 per cent month-on-month growth - no longer apply uniformly, especially for infrastructure companies burning capital on compute or hardware before revenue scales.
Teng Wade offered the example of Anthropic's early financing. When Bessemer evaluated the company, margins were deeply negative and compute expenses were mounting. One partner on her team argued that frontier AI models would command price premiums large enough to justify the burn, effectively substituting for legacy software categories. The thesis was that even with unprofitable unit economics in the near term, the total addressable market would reward the top three players. Anthropic is now reportedly preparing for a public offering at a valuation near two trillion dollars, and recently told investors it had achieved adjusted profitability, though that metric excludes certain costs.
The Anthropic case illustrates a broader shift: investors are underwriting market size and competitive position over near-term margin discipline, at least in categories deemed transformational. That calculus works only if the category thesis proves correct and the company secures a top-tier position. For founders outside those narrow bands, the bar remains high and the capital scarce.
The Red Flags Investors Watch For
Singh was explicit about one metric manipulation he considers disqualifying: cumulative revenue or cumulative ARR charts. Presenting data in cumulative form masks churn, stalled growth, or declining cohorts. Time-series data - monthly or quarterly revenue plotted over time - reveals the true trajectory. Cumulative charts, he said, are "a big lie."
The warning reflects a broader concern about intellectual honesty in bull markets. With AI-related companies commanding headline valuations, there is pressure to engineer metrics that justify those numbers. Singh urged founders to resist that temptation, arguing that inflated presentations erode trust and set up future down rounds when reality asserts itself.
Sardana raised a related concern: founders are choosing what to build based on what is currently getting funded, rather than on genuine market insight or technical advantage. That dynamic creates clusters of similar companies chasing the same narrow opportunity, often with weak differentiation. When the cycle turns, those clusters collapse.
The venture investors' caution aligns with patterns we have observed in Asia-Pacific markets. In the first half of 2026, at least four Singapore-based startups pivoted their pitch decks from SaaS productivity tools to "AI-native workflow platforms" within a six-week window, according to term sheets reviewed by Opentechwire. Three of those companies had not shipped meaningful AI functionality at the time they updated their positioning. That kind of surface-level repositioning rarely survives due diligence at the Series A stage, but it consumes founder time and investor attention.
Divergent Advice on Audacity
The three investors offered contrasting counsel on how aggressively founders should price their asks.
Singh urged restraint. He reminded founders that building a durable company is "one of the most excruciatingly difficult things" one can attempt, and advised against rushing into fundraising without strong product-market fit. He stressed holding the bar high for the problem being solved, rather than optimising for what is fashionable.
Teng Wade took the opposite view. Her traditional advice - be conservative with projections and capital requests - has not held up in the current environment. She now tells founders to be audacious in their initial ask, test the market response, and adjust from there. The logic is that in a bifurcated market, top companies can command extraordinary terms, and founders will not know which category they fall into until they test.
The contradiction is revealing. Both investors are operating in the same market, yet their tactical guidance diverges sharply. That divergence itself is evidence of the dysfunction Singh described: there is no consensus playbook, and outcomes vary wildly based on sector, timing, and investor perception.
What a Correction Might Look Like
Singh's forecast of a 2027 correction hinges on the observation that venture optimism has reached levels he has not seen in twenty years. The current environment, he argued, is producing too many "false positives" - companies that appear successful based on early traction but lack the fundamentals to sustain growth.
A correction would likely take several forms. Valuation multiples would compress, particularly for companies that raised at aggressive prices without commensurate revenue or user growth. Investors would tighten diligence standards, reverting to traditional metrics and profitability timelines. The tranche structures that define today's rounds would disappear as investors regain pricing power. And sectors currently in favour - particularly those tied to AI hype rather than AI deployment - would see sharp pullbacks.
For founders, the implication is that the current window for raising at inflated terms is finite. Those who secure capital now at high valuations will face pressure to grow into those numbers quickly, or risk down rounds when they return to market. Those who wait may find a more disciplined environment, with lower prices but clearer expectations.
Navigating the Froth
At Opentechwire, we see the Series A market as a study in contradictions. Capital is abundant for a narrow set of companies in favoured categories, yet scarce for everyone else. Metrics matter, except when they do not. Founders should be conservative, or audacious, depending on which partner you ask.
The through-line is that founders need clarity about their own fundamentals - revenue quality, retention, unit economics, competitive moat - and the honesty to present those fundamentals without distortion. In a frothy market, the temptation to inflate is strong. But the investors who matter can spot cumulative-revenue tricks and superficial pivots. And when the correction arrives, the companies that survive will be those that built for durability rather than for the pitch deck.
Singh's warning about 2027 may or may not prove accurate. Timing market corrections is notoriously difficult, and AI adoption could yet justify current valuations if deployment accelerates. But the structural signals - term fragmentation, metric inflation, sector crowding - suggest the current equilibrium is unstable. Founders raising now should plan for both scenarios: continued exuberance and sudden sobriety.