Meta Unveils Non-Voting Share Class to Finance AI Expansion
The social media giant plans to issue dividend-distributed stock that preserves founder control while funding infrastructure, talent acquisition, and product scaling across its artificial intelligence portfolio.
A Capital Structure Shift to Support Infrastructure Spending
Meta disclosed plans to introduce a new class of non-voting capital stock during its third-quarter earnings call, a financial instrument designed to raise capital without diluting the voting power of existing shareholders. Chief financial officer Susan Li explained that the shares would be distributed to all current shareholders through a stock dividend mechanism, creating a publicly traded security that the company can deploy for capital raising, employee compensation, acquisitions, and other corporate purposes.
The timing aligns with Meta's aggressive push into artificial intelligence infrastructure and product development. Li framed the move as a way to "give us flexibility to invest behind the unprecedented momentum we're seeing across every part of our business, driven by AI," while simultaneously preserving what she described as the company's "founder-led structure." The dual-class structure that keeps Mark Zuckerberg in control has long been a defining feature of Meta's governance, and this latest share class extends that architecture into a new funding mechanism.
At Opentechwire, we've tracked similar capital manoeuvres across Asia's tech landscape - particularly among family-controlled conglomerates in South Korea and Southeast Asia that have used non-voting shares to tap public markets without ceding board influence. Meta's approach borrows from that playbook, though the stated purpose here is less about succession planning and more about sustaining capital-intensive AI investments without triggering shareholder votes on major strategic pivots.
Strong Revenue Growth Offset by Rising Costs
Meta reported revenue of USD 64 billion for the third quarter, a year-on-year increase of 26 per cent that exceeded analyst expectations. Yet costs and expenses surged 68 per cent over the same period, a disparity that underscores the financial pressure driving the new share class. Reality Labs, the division responsible for augmented reality glasses, virtual reality headsets, and related software, continues to generate losses, though Meta projects those will narrow to between USD 18 billion and USD 19 billion from 2025 levels.
The divergence between revenue growth and cost escalation is not unusual for companies betting heavily on emerging platforms, but it does highlight the scale of Meta's wager on AI and immersive computing. The non-voting stock offers a path to finance both without resorting to debt issuance or further dilution of voting equity, a trade-off that benefits existing Class A and Class B shareholders while potentially attracting capital from investors willing to accept governance-free exposure to Meta's growth trajectory.
Product Momentum and User Traction
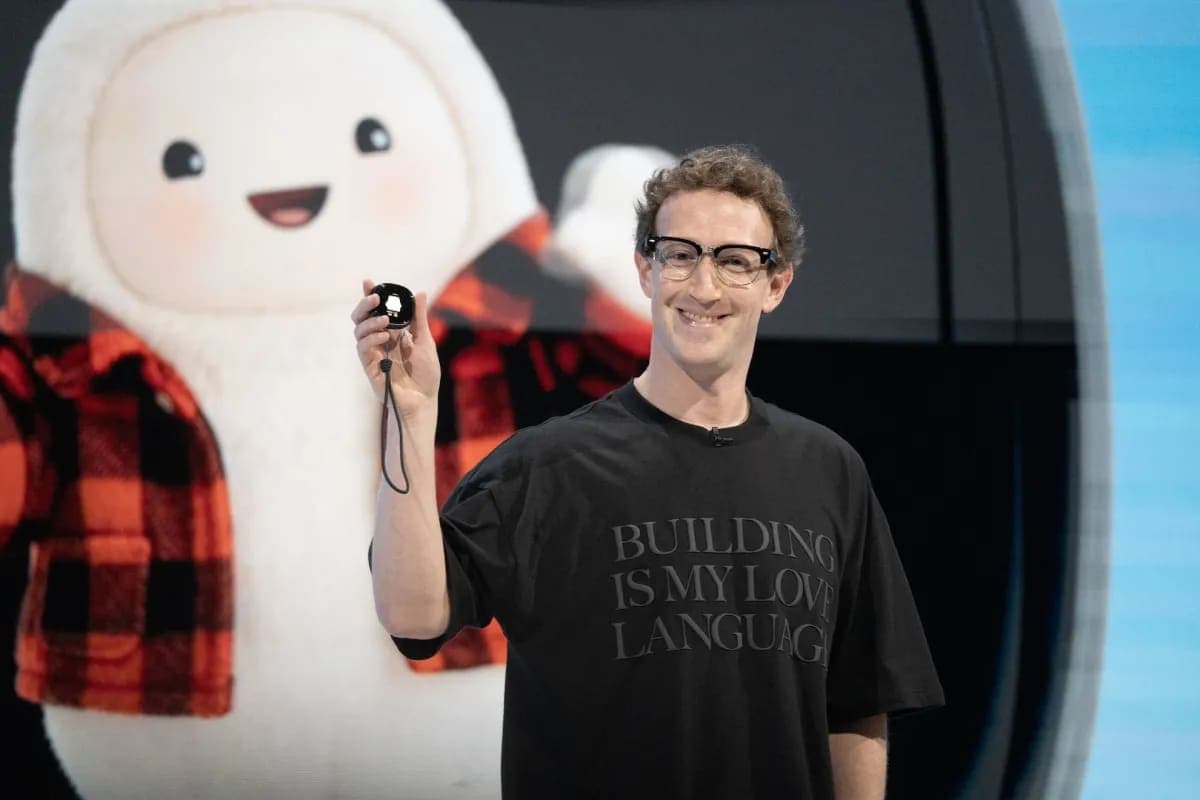
Meta has released a flurry of AI models over the past year, including proprietary systems and open-weight releases whose underlying parameters are available for external use. The company also introduced a coding agent tailored for software developers and rolled out a suite of avatar-driven interfaces for its AI assistant, branded as Meta Muse, at its annual Connect event. Zuckerberg stated during the earnings call that more than 10 million users in the United States and Canada had set up Muse personal agents within six weeks of launch, and that the product has held the top position in the App Store on most days since release.
That adoption curve suggests Meta has found a viable product-market fit for its consumer-facing AI tools, a milestone that the company is now attempting to scale globally. Zuckerberg indicated that Meta is entering an "operational phase" focused on expanding Muse to "serve billions of people," a target that would require not only compute infrastructure but also localised model training, content moderation, and regulatory compliance across dozens of jurisdictions.
The open-weight releases are particularly noteworthy in the context of Meta's broader strategy. By making model parameters publicly accessible, the company invites external developers to build applications on top of Meta's AI stack, a move that can accelerate ecosystem growth and reduce the company's own engineering burden. It also positions Meta as a counterweight to closed-model providers, though the competitive dynamics remain fluid given the pace of model releases from rivals in North America, China, and Europe.
Regulatory Headwinds and Youth-Related Litigation
Li acknowledged during the call that regulatory scrutiny remains a persistent risk, particularly around youth-related issues. Meta faces multiple trials scheduled in the coming months in the United States, and Li noted that the company is monitoring "active legal and regulatory matters that could significantly impact our business and financial results." The comment was brief but pointed, signalling that legal costs and potential settlements could represent another drain on capital alongside infrastructure spending.
Regulatory pressure on social media platforms has intensified across multiple markets, with governments in Europe, Asia, and North America proposing or enacting rules around content moderation, data localisation, and platform liability. For Meta, the youth-safety dimension carries particular reputational risk, as it intersects with broader debates about screen time, mental health, and algorithmic amplification. The outcome of pending litigation could shape not only financial liabilities but also the design constraints under which Meta builds its next generation of AI-driven products.
Implications for Founder Control and Capital Allocation
The introduction of non-voting shares raises questions about the long-term balance of power within Meta's shareholder base. In theory, the structure allows Zuckerberg and other holders of voting stock to maintain decision-making authority even as the company issues large volumes of new equity. In practice, it could also create a tiered market in which voting and non-voting shares trade at different valuations, reflecting investor preferences for governance rights versus pure economic exposure.
Similar structures have been used by technology companies in the United States and Asia, often to facilitate acquisitions or employee equity programmes without triggering dilution of founder control. The risk is that over time, the proliferation of non-voting shares can concentrate power in ways that limit accountability, particularly if the company's strategic direction diverges from the interests of non-voting shareholders. Meta's framing of the move as a tool for "flexibility" suggests the company anticipates using the shares actively, rather than as a one-off financing event.
For investors, the calculus will depend on confidence in Meta's AI strategy and its ability to convert heavy capital spending into durable revenue streams. The company's third-quarter results demonstrate strong top-line growth, but the cost trajectory and ongoing losses in Reality Labs underscore the magnitude of the bet. The non-voting share class is, in effect, a mechanism to sustain that bet without relinquishing the governance structure that has defined Meta since its public listing.
A Test of Investor Appetite for Governance-Free Growth
Meta's move arrives at a moment when capital markets are reassessing the terms under which they fund technology companies with founder-led governance. The non-voting share class offers a clear value proposition: exposure to Meta's AI-driven growth without the complications of shareholder activism or board battles. Whether that proposition proves attractive will depend on execution, regulatory outcomes, and the broader trajectory of AI monetisation across the industry.
At Opentechwire, we see this as part of a larger pattern in which platform companies are using capital structure innovation to navigate the tension between aggressive investment cycles and governance stability. The challenge for Meta will be demonstrating that its AI products can scale profitably and that the billions being poured into infrastructure, models, and user acquisition translate into sustainable competitive advantage. For now, the non-voting shares are a financial instrument. Their ultimate success will be measured in product traction, margin expansion, and the company's ability to deliver on the vision that justifies the capital outlay.