The Micromanager Behind China's Robot Price War
Wang Xingxing built Unitree into a humanoid robotics leader by personally choosing screw lengths and material colours, but that obsessive control may not scale with the company's ambitions.
The Quiet Billionaire Who Decides Every Screw
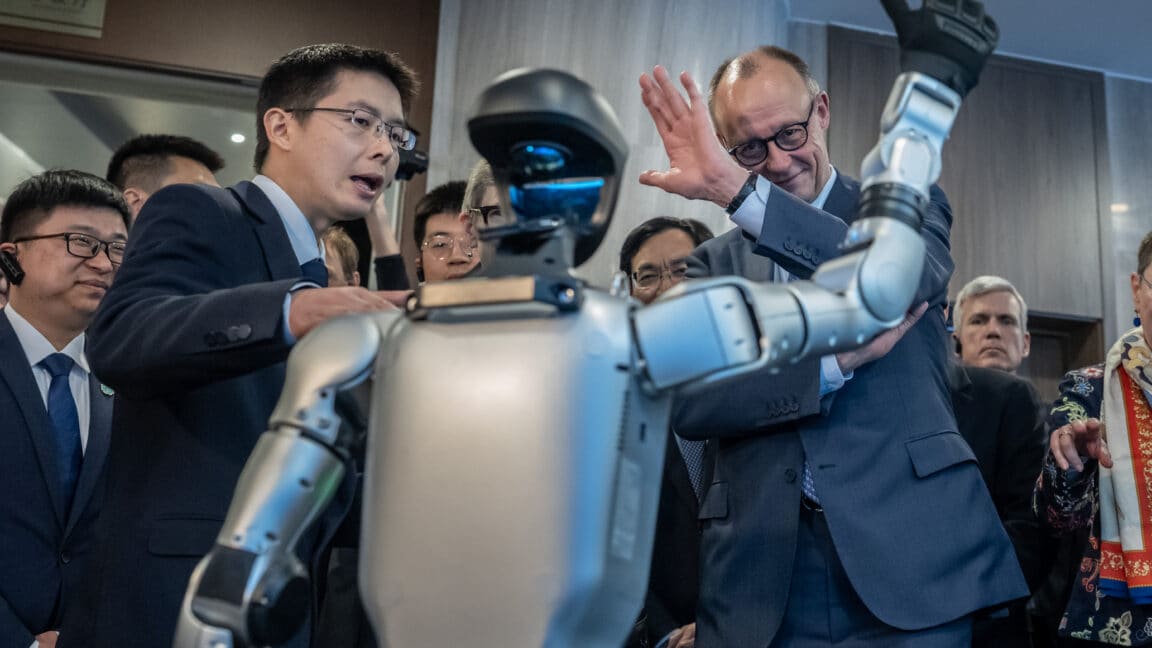
Wang Xingxing does not fit the archetype of the gregarious tech founder. Yet the introverted engineer has become one of the most influential figures in global robotics, steering Unitree Robotics to a position where it ships some of the world's most affordable humanoid robots and four-legged machines. When Unitree listed on the Shanghai Stock Exchange STAR Market on 19 August, Wang's net worth surged into the billions, cementing his status in an industry where China now holds a manufacturing and pricing edge that few rivals can match.
What distinguishes Wang is not charisma but an almost pathological attention to cost and detail. Reporting from Beijing-based business magazine Caijing, later translated by ChinaTalk, a US think tank and media organisation, reveals a founder who personally approves the colour of every material, the length of every screw, and the trajectory of nearly every strategic decision. Employees and investors describe a leadership style that blurs the line between founder vision and micromanagement, a model that propelled Unitree from obscurity to IPO but may struggle to carry it through the next phase of expansion.
At Opentechwire, we have tracked dozens of hardware startups across Shenzhen, Seoul and Bengaluru, and the pattern is familiar: a brilliant, detail-obsessed founder drives early-stage efficiency, then hits a ceiling when the organisation outgrows one person's bandwidth. Unitree's trajectory suggests it may be approaching that inflection point.
Cost as Core Competence
Unitree's competitive advantage rests on a simple proposition: build capable robots and sell them for less than anyone else. The company's humanoid platforms and quadruped units undercut Western and Japanese rivals by margins wide enough to reshape customer expectations. That pricing discipline flows directly from Wang's engineering philosophy, which treats every yuan of bill-of-materials cost as a problem to be solved.
The Caijing profile describes a founder who scrutinises component choices with the intensity of a cost accountant. Material selection, fastener specifications, and even packaging design pass through his review. This is not delegation to a trusted lieutenant or a cross-functional team; it is direct, personal oversight of decisions that most chief executives would consider operational minutiae.
For a startup competing in capital-intensive robotics, this approach has clear benefits. It prevents the feature creep and specification bloat that plague hardware development. It forces trade-offs to be made early, before they compound into production delays or margin erosion. And it aligns the entire organisation around a single, legible goal: ship a robot that works, and do it cheaper than the competition.
But the same rigour that accelerates a 50-person startup can paralyse a 500-person company. Decision-making that flows through a single node does not scale linearly. As product lines multiply and customer segments diversify, the bottleneck becomes the founder himself.
Recognition and Risk
Wang's prominence extends beyond the robotics industry. In 2025, he appeared at a business symposium hosted by President Xi Jinping, a signal of state-level recognition for Unitree's achievements. That visibility reflects China's broader ambition to lead in intelligent manufacturing and embodied AI, sectors where humanoid robots are seen as both a technical frontier and an industrial policy priority.
The IPO on the STAR Market, a board designed for technology firms with high growth potential, provided Unitree with capital and credibility. It also placed the company under the scrutiny that comes with public-market governance, where investors expect transparency, predictable execution, and evidence that leadership can scale alongside revenue.
The tension is already visible. Interviews with employees, as reported by Caijing, suggest frustration with the pace of decision-making and the limited autonomy afforded to mid-level managers. For engineers accustomed to iterating quickly, waiting for founder approval on granular details introduces friction. For investors, the question is whether Wang can transition from artisan to architect, delegating operational control while retaining strategic coherence.
The Shenzhen Playbook and Its Limits
Unitree's model is not unique to robotics. It mirrors the cost-driven, iteration-heavy approach that powered Shenzhen's electronics ecosystem for two decades. Firms like DJI and Anker grew by combining engineering talent with supply-chain proximity, using rapid prototyping and relentless cost optimisation to outpace incumbents. Wang's obsession with screw lengths and material costs is a direct descendant of that playbook.
But the robotics market is not the drone market. Humanoids and quadrupeds operate in unstructured environments, require ongoing software updates, and face regulatory scrutiny in key export markets. Success depends not only on unit economics but on after-sales support, safety certification, and ecosystem development. These are organisational challenges, not purely technical ones, and they require distributed decision-making, regional teams, and a willingness to cede control.
There is also the matter of talent retention. Hardware engineers in China's tier-one cities have options. Firms like Xiaomi, Huawei, and ByteDance compete for the same talent pool, often with more generous compensation and clearer paths to senior roles. If Unitree's culture rewards proximity to the founder over independent execution, it risks losing the mid-level leaders who would otherwise form the backbone of a scaling organisation.
What Comes Next
Unitree now faces a choice common to founder-led hardware companies: evolve the operating model or accept that growth will be constrained by the founder's capacity. The IPO provides resources to hire, expand, and enter new markets. But capital alone does not solve organisational design.
One path forward is to adopt a more federated structure, where product lines operate semi-independently under clear financial and strategic guardrails. Wang could retain final approval on core technology choices while delegating execution to general managers with profit-and-loss accountability. This model has worked for other Chinese hardware firms navigating the transition from startup to scale-up.
Another option is to lean into the founder-driven model, treating Unitree as a high-discipline, vertically integrated manufacturer that competes on cost and iteration speed rather than breadth. This would mean slower international expansion, narrower product portfolios, and acceptance that some opportunities will be left on the table. It would also mean accepting higher attrition among employees who prefer autonomy.
The third possibility is that Wang's style, however unconventional, proves more durable than the standard Silicon Valley narrative suggests. If Unitree's margins remain strong, its products continue to improve, and customers keep buying, the case for organisational change weakens. The market, after all, does not reward governance aesthetics; it rewards results.
The Broader Implications
Unitree's rise is part of a larger story about China's position in the global robotics supply chain. The country has moved from low-cost assembly to indigenous design and brand ownership, particularly in mobile and humanoid platforms. Firms like Unitree, Fourier Intelligence, and AgileX Robotics are no longer competing solely on price; they are iterating on form factors, control algorithms, and end-user applications.
For buyers outside China, the calculus is shifting. A Unitree humanoid may cost half what a US or European competitor charges, but procurement decisions now involve supply-chain risk, export-control compliance, and long-term support considerations. The price advantage is real, but so are the trade-offs.
For competitors, the lesson is that cost leadership in robotics is not a temporary arbitrage. It is the result of sustained engineering discipline, supply-chain integration, and a willingness to make uncomfortable trade-offs. Matching Unitree on price will require more than offshoring assembly; it will require rethinking design, materials, and go-to-market strategy from first principles.
Wang Xingxing's obsession with screw lengths may seem eccentric, even counterproductive. But it reflects a deeper commitment to cost as a strategic weapon, not an afterthought. Whether that commitment can coexist with the demands of a public, fast-growing company remains an open question. The answer will shape not only Unitree's future but the competitive dynamics of the global robotics industry.