Consumer AI Hits a Revenue Ceiling Despite Better Models
Subscription growth remains stubbornly linear while operating costs soar, pushing frontier labs toward enterprise contracts and forcing new entrants to rethink monetisation from day one.
The Paradox of Performance and Profit
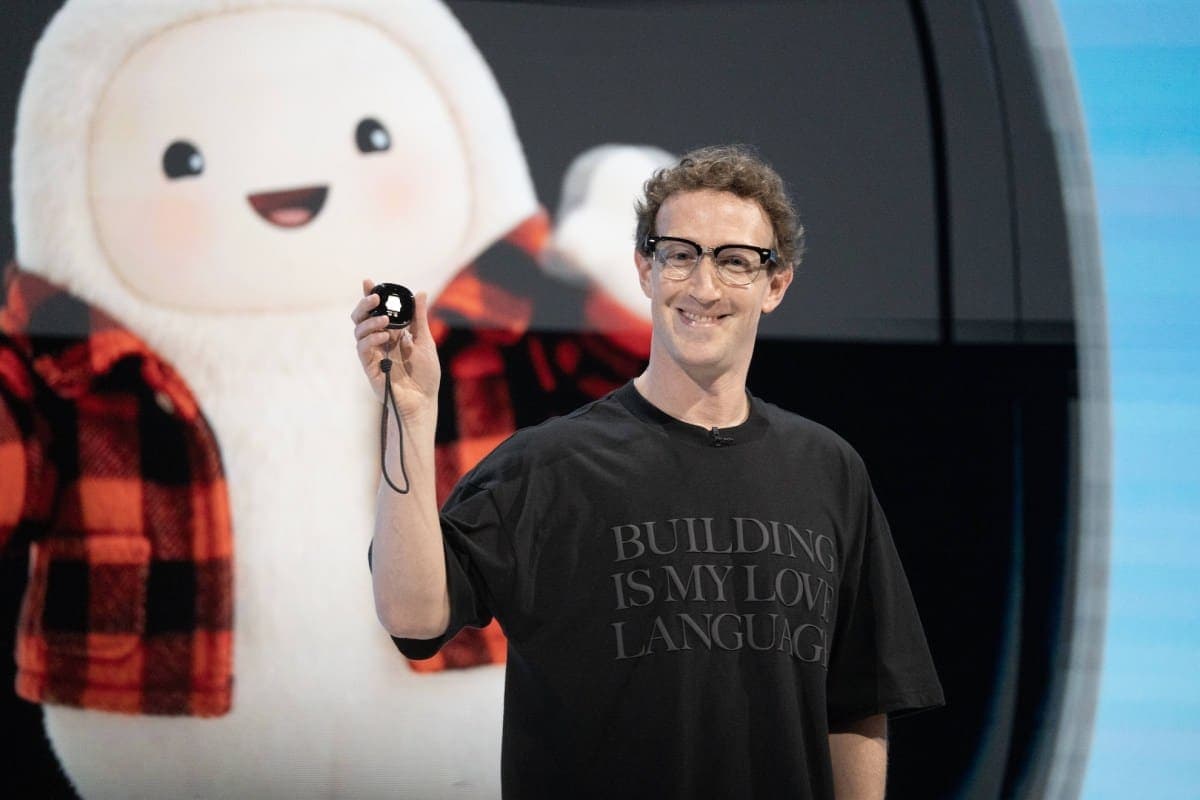
The past week has seen a cluster of consumer AI launches that might suggest the category is entering a second wind. Meta unveiled Muse, a personal assistant paired with a plush mascot called Jolly, which has drawn unexpected traction. OpenAI followed with Dots, a similarly cartoon-styled agent aimed at everyday users. Meanwhile, Instinct, an agentic platform focused on booking travel and managing subscriptions, recently closed a funding round that valued the company at $10 billion.
To observers watching the frontier model race, the appeal is intuitive. Agentic systems have crossed a reliability threshold that makes them useful for routine errands, not just novelty queries. The comparison to late 2022, when ChatGPT first demonstrated what large language models could do for a general audience, feels apt. A new product category appears to be opening.
Yet the enthusiasm masks a structural problem that has already reshaped strategy at the largest AI labs. Consumer AI, for all its technical progress, has run into an economic wall that better models have not managed to breach.
The Numbers Tell a Flat Story
Data compiled by PNC and surfaced in Andreessen Horowitz's State of Markets report this autumn show that as of May, 2.2 per cent of consumers were paying for AI services. The average monthly spend stood at $31. Both figures represent growth from the prior year, but the trajectory is linear rather than exponential.
What stands out is how little these metrics have responded to model improvements. The leap in capability from one generation of frontier models to the next, substantial by any technical measure, barely registers in subscriber growth or willingness to pay. Performance gains that would have seemed transformative two years ago are not translating into proportional revenue expansion.
Bank of America reported similar findings in March, estimating that roughly 3 per cent of US consumers were paying for AI, a 40 per cent year-on-year increase. A September survey by Menlo Ventures offered a rosier view, finding that a quarter of adults use AI daily and half of those users pay for it. Even under the more optimistic reading, the addressable market remains constrained.
The revenue ceiling becomes clearer when benchmarked against mature subscription businesses. If AI services reached Netflix-scale penetration at 325 million subscribers and maintained the $31 average monthly spend, annual revenue would sit around $11 billion. That figure is less than a third of what OpenAI reportedly spends to operate each year.
Operating Costs Outpace Consumer Revenue
The core issue is not demand but cost structure. Running inference at scale, particularly for the latest models, remains expensive relative to the lightweight infrastructure that powered earlier internet services. Social networks and cloud storage providers could reach profitability with far smaller per-user revenue because their marginal costs were lower. AI inference, by contrast, involves compute-intensive operations that do not compress as elegantly.
Even hundreds of millions of paying users may not guarantee a break-even consumer business if the underlying economics do not shift. This is not a problem that can be solved purely by scale. The cost per query has come down as hardware improves and models become more efficient, but the gap between what consumers will pay and what it costs to serve them has not closed fast enough to make consumer AI a standalone profit centre.
At Opentechwire, we have tracked how this reality has driven a sector-wide pivot toward enterprise sales. Companies that initially positioned themselves as consumer-first are now emphasising vertical-by-vertical expansion, selling to businesses that will pay significantly more per seat and tolerate longer contract cycles. OpenAI itself has leaned into this shift. Enterprise bookings reportedly doubled between July and the present, and even the Dots launch included a strong pitch to software engineers and creative agencies, not just individual users.
The strategy mirrors an older playbook: build a popular consumer product, then monetise it by selling a premium version to businesses. Slack, Zoom, and Dropbox all followed variations of this path. The difference is that those companies reached consumer profitability before scaling enterprise. In AI, the enterprise pivot is happening because consumer profitability remains elusive.
Where Muse and Instinct Fit
The recent wave of consumer AI products raises the question of whether new entrants are betting on a shift in the underlying economics, or whether they have simply chosen to defer the monetisation question.
Meta's Muse benefits from the company's advertising infrastructure, which gives it room to experiment without immediate pressure to extract subscription revenue. Meta has also signalled interest in enterprise applications, suggesting that even a product designed for consumers may eventually follow the same trajectory as its peers. The company's ability to cross-subsidise from its core ad business means Muse can afford to operate at a loss longer than a standalone startup.
Instinct presents a different model. The platform plans to take a percentage of transactions completed through the agent, such as flight bookings or subscription cancellations. This shifts the revenue model away from flat subscription fees and toward usage-based monetisation, which could raise the ceiling if transaction volume scales. The company also avoids the capital expense of training frontier models, relying instead on existing infrastructure. That lowers the fixed cost base and buys time to prove out the unit economics.
Still, both companies will eventually need to demonstrate that the consumer AI business can sustain itself without leaning on enterprise contracts or adjacent revenue streams. The current data suggests that is a harder problem than simply building a better model.
The Enterprise Escape Hatch
The shift toward enterprise has become the de facto solution to the consumer AI revenue problem. Businesses pay more, sign longer contracts, and often require customisation that justifies premium pricing. They also tolerate higher latency and less polished interfaces if the underlying capability solves a real workflow problem.
Anthropic has been explicit about this strategy, focusing on enterprise partnerships and embedding its models into vertical-specific tools. OpenAI, despite its consumer origins, now derives a growing share of revenue from business clients. Even Google's Gemini and Microsoft's Copilot are primarily positioned as productivity tools for enterprise users, not general-purpose consumer assistants.
The risk is that the consumer market becomes a loss leader, useful for brand awareness and user acquisition but not a sustainable business on its own. If that proves true, the companies launching consumer AI products today are either betting on a future change in willingness to pay, or they are building the consumer layer as a stepping stone to enterprise sales.
What Happens Next
The economics of consumer AI are not improving at the pace that model performance is. That divergence is shaping strategy across the industry, pushing companies toward enterprise contracts and usage-based pricing models that can support the cost structure.
For investors, the lesson is that consumer traction alone is not a proxy for a viable business. The number of users and the frequency of use matter less than the delta between what those users will pay and what it costs to serve them. Until that gap closes, consumer AI will remain a difficult category to monetise at scale.
The companies launching consumer products this week are navigating that reality in different ways. Some have enterprise revenue to fall back on. Others are experimenting with transaction-based models or relying on adjacent businesses to subsidise the consumer offering. But none of them have solved the underlying problem: AI is expensive to run, and consumers are not yet willing to pay enough to cover the cost.
That is not a technical problem. It is an economic one, and it is proving harder to solve than building a better model.