Salmon Group Raises USD 140 Million to Scale Lending Across the Philippines
The Manila-based fintech will deploy fresh capital into credit expansion and new product lines targeting motorcycle owners and MSMEs.
Capital for Expansion in a Tight Credit Market
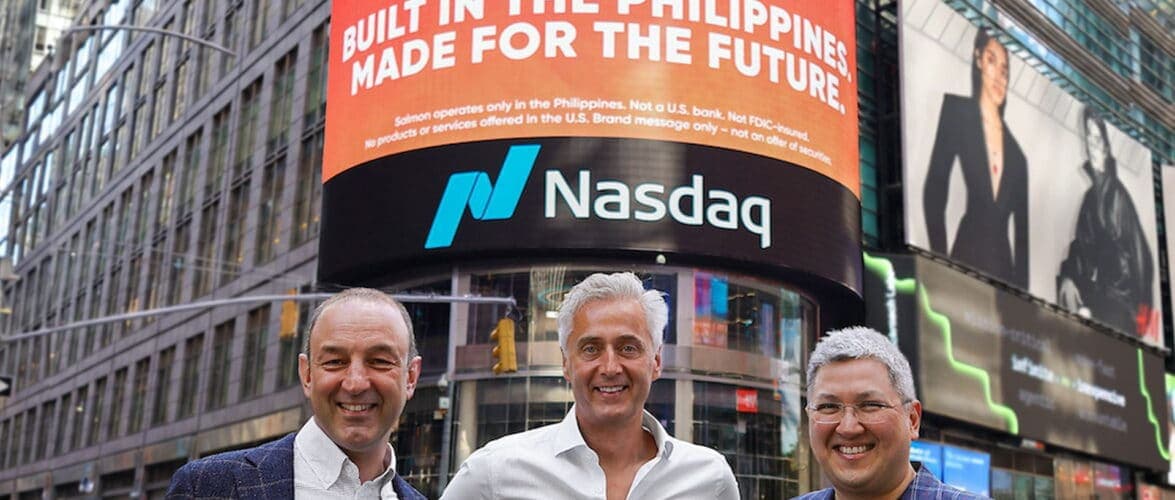
Salmon Group, the financial technology firm behind a banking and lending platform in the Philippines, has closed USD 140 million in financing to push deeper into consumer and small-business credit. The round positions the company to scale operations that it says are already profitable, a claim that stands out in a regional fintech landscape where many lenders continue to burn capital in pursuit of unit economics.
The Manila-based firm operates a digital platform that combines banking infrastructure with credit products, serving a market where formal financial access remains patchy. Around 47 per cent of Filipino adults remain unbanked or underbanked, according to Bangko Sentral ng Pilipinas survey data from 2023, leaving a substantial pool of borrowers reliant on informal credit or excluded entirely.
Two Businesses, One New Push
Salmon plans to channel the fresh capital into its existing credit and in-store lending arms, both of which the company describes as profitable. In-store lending, often delivered at point of sale through merchant partnerships, has emerged as a competitive segment across Southeast Asia, with players racing to sign retail and e-commerce partners before rivals lock them in.
Beyond scaling those lines, Salmon intends to launch two new verticals: motorcycle lending and credit products tailored to micro, small, and medium enterprises. The motorcycle category is particularly strategic. Two-wheelers remain the dominant form of transport for millions of Filipinos outside Metro Manila, yet financing options are often limited to dealer arrangements or high-interest informal loans. Nationwide MSME lending, meanwhile, addresses a segment that banks have historically underserved due to perceived risk and thin documentation.
Profitability Claims in Context
Salmon's assertion that its credit and in-store businesses are profitable invites scrutiny. Across the region, fintech lenders have frequently reported gross profit at the product level while continuing to post net losses once technology, customer acquisition, and overhead are included. The company has not disclosed whether profitability is measured at contribution margin, operating income, or net income, nor has it shared default rates or loan-loss provisions.
Still, the ability to raise USD 140 million suggests that backers see sustainable unit economics, or at least a credible path to them. Debt and quasi-equity structures have become the dominant form of growth capital for lending fintechs in Southeast Asia, allowing companies to match funding duration with loan tenors and avoid dilution. Salmon has not specified the structure of this financing, whether pure debt, convertible instruments, or a blend.
Competitive Terrain
The Philippine fintech credit market is increasingly crowded. Local players such as Tonik, the first digital-only bank to secure a full licence in the country, and Robocash Philippines compete alongside regional entrants and incumbent banks launching digital arms. In-store lending, in particular, has attracted venture-backed specialists like Cashalo and established consumer finance firms expanding online.
Motorcycle lending has seen early traction from specialised finance companies, but no dominant digital-first player has yet emerged. Salmon's move into this vertical, combined with MSME products, suggests a strategy to build multiple credit books rather than rely on a single asset class. Diversification can dampen portfolio risk, though it also demands separate underwriting models, collections infrastructure, and regulatory navigation for each segment.
Regulatory and Macro Headwinds
The Philippine central bank has tightened oversight of digital lending in recent years, particularly after a wave of predatory lending apps drew public outcry. New rules require lenders to cap interest rates, prohibit abusive collection practices, and ensure transparent disclosure. Salmon, operating under a broader banking licence structure, faces a different compliance regime than standalone lending apps, but the regulatory climate remains watchful.
Macro conditions add another layer. Philippine inflation has moderated from its 2023 peak, yet real interest rates remain elevated, squeezing household disposable income. Consumer loan delinquencies have ticked up across the sector, though official non-performing loan ratios remain below regional averages. Any fintech scaling credit now must price in the possibility of a downturn, particularly if global risk appetite shifts or remittance inflows, a critical pillar of Filipino household income, slow.
What the Capital Buys
At Opentechwire, we have tracked how growth-stage fintechs deploy large funding rounds, and the pattern is instructive. Roughly half typically goes to loan book expansion, either directly funding loans or backing warehouse lines that can be securitised later. Another portion funds technology, particularly underwriting engines and fraud detection, both critical in markets with limited credit bureau coverage. The remainder covers customer acquisition, partnerships, and working capital.
Salmon's emphasis on launching new products suggests it will allocate capital across all three buckets, with a meaningful share reserved for building out motorcycle and MSME underwriting from scratch. These segments require different data sources: for motorcycles, telematics and usage patterns; for MSMEs, transaction history, supply-chain linkages, and sometimes alternative data like utility payments or mobile-money flows.
The Bigger Picture
This financing arrives as Southeast Asian fintech funding remains well below the peaks of 2021 and early 2022, when venture capital poured into the region. Debt and structured finance have filled the gap for revenue-stage lenders, but the bar for new rounds has risen. Investors now demand clear paths to profitability, disciplined underwriting, and proof that customer acquisition costs can be recovered within loan lifetimes.
Salmon's ability to secure USD 140 million suggests it has cleared those hurdles, at least in the eyes of its backers. Whether that capital translates into durable market share will depend on execution: underwriting discipline, merchant and partner network expansion, and the capacity to manage multiple credit portfolios simultaneously without letting risk controls slip.
The Philippine market offers scale, but it also punishes missteps. High smartphone penetration and a young, digitally native population provide tailwinds, yet income volatility, thin credit histories, and regulatory scrutiny demand caution. Salmon's next 18 months will test whether it can convert capital into sustainable growth, or whether profitability at today's scale proves harder to maintain as the loan book grows.