Optical Chip Suppliers in China Face Market Turmoil as Export Control Speculation Intensifies
Shares of upstream and downstream players tumbled for two consecutive sessions amid investor concerns over Washington's next move in tech restrictions.
A Two-Day Slide
Share prices for Chinese firms that make optical transceivers and related components fell for a second consecutive session on 9 October, deepening a rout that began earlier in the week. By the midday break, the CSI 300 Index had dropped 1.3 per cent to its lowest mark since August of the previous year, according to mainland exchange data.
The losses came despite reassurances issued by several major suppliers. Investors appeared unconvinced, continuing to offload positions in a sector that has been among the most visible beneficiaries of the global build-out of AI infrastructure over the past eighteen months.
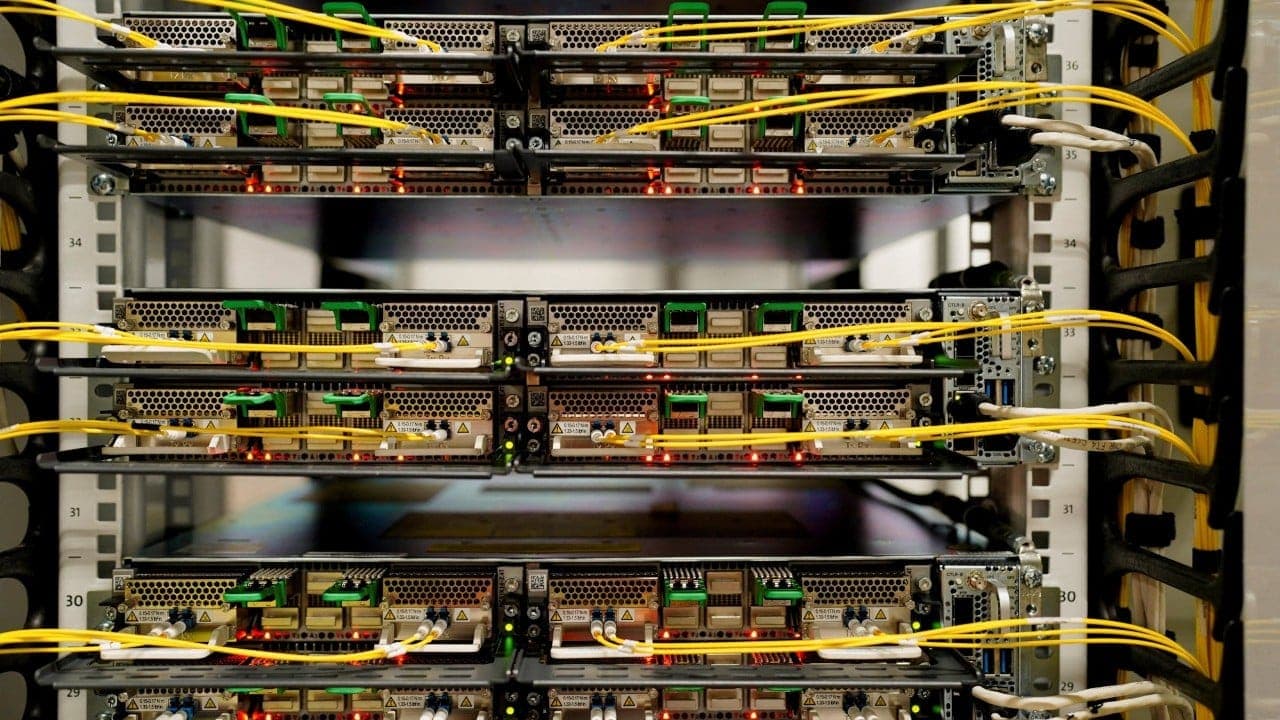
Optical transceivers convert electrical signals into light for transmission over fibre-optic cables and back again at the receiving end. They are critical components in the high-speed networks that link servers inside hyperscale data centres, and demand has surged as training runs for large language models and inference workloads require ever-greater bandwidth between compute nodes.
The Export Control Shadow
The immediate trigger for the sell-off appears to be renewed speculation that Washington may expand its suite of semiconductor and equipment export controls to cover next-generation optical transceiver modules. No official announcement has been made by the US Department of Commerce, and no timeline has been confirmed by any agency.
At Opentechwire, we've tracked the evolution of US export policy since the October 2022 controls on advanced logic chips and chipmaking tools. Each subsequent update has broadened the scope, adding new performance thresholds, new product categories, and new end-use restrictions. The pattern has taught market participants to price in worst-case scenarios before official guidance arrives.
Optical components occupy an unusual position in this landscape. They sit downstream of semiconductor fabs but upstream of system integrators. A transceiver module may contain indium phosphide lasers, silicon photonics chips, digital signal processors, and precision optics, each with its own supply chain. Restricting access to any of these sub-components can bottleneck an entire class of products.
Upstream Laser and Downstream Module Makers Both Hit
The sell-off affected firms across the value chain. Upstream suppliers of laser diodes and photonic integrated circuits saw their valuations compress alongside downstream assembly houses that package transceivers into pluggable modules for sale to equipment vendors and cloud operators.
This breadth suggests investors are uncertain where any potential control measures might be applied. In previous rounds, Washington has targeted both finished goods and enabling components, and has used entity-list designations to block specific buyers even when the underlying technology remains exportable in principle.
Chinese suppliers have captured meaningful share in 400-gigabit-per-second and 800-gigabit-per-second transceiver modules over the past two years, undercutting established US and Taiwanese vendors on price while meeting technical specifications for coherent and parallel optics. Several mainland firms have announced plans to begin volume production of 1.6-terabit modules in the first half of 2027, a roadmap that aligns with the deployment schedules of major hyperscalers.
Reassurances and Market Scepticism
Multiple companies issued statements this week aimed at calming investor concerns. The reassurances typically emphasised that no formal restrictions have been announced, that existing product lines remain compliant with current regulations, and that diversification efforts are underway.
Markets responded with continued selling. The gap between corporate messaging and share-price action reflects a broader loss of confidence in forward guidance when regulatory ground can shift without advance notice.
For firms that derive a significant portion of revenue from sales to US-headquartered cloud providers or their contract manufacturers, even the possibility of new controls introduces planning paralysis. Long-lead procurement, capacity allocation, and R&D investment all become harder to justify when a single Federal Register notice can render a product line unexportable.
The Bandwidth Bottleneck in AI Infrastructure
Optical interconnects have emerged as a critical bottleneck in AI system design. Training a frontier model can require thousands of GPUs or accelerators to exchange gradient updates and activation tensors across a high-bandwidth fabric. As cluster sizes grow, the ratio of network bandwidth to compute throughput becomes a binding constraint.
This has driven transceiver demand far beyond the growth rates seen in traditional enterprise networking. Module shipments for AI data centres are projected to grow at a compound annual rate above 40 per cent through 2028, according to supply-chain data tracked across the region.
Chinese suppliers entered this market at an opportune moment. Incumbent vendors faced capacity constraints and long lead times, creating an opening for alternative sources willing to invest in production scale. Mainland firms also benefited from vertical integration with domestic fibre and connector suppliers, reducing bill-of-materials costs.
If export controls are imposed, hyperscalers would face a choice: requalify alternative suppliers from allied jurisdictions, accept higher costs and longer delivery windows, or redesign network architectures to reduce per-node bandwidth requirements. Each option carries execution risk and delays deployment timelines.
Regional Implications
The potential for new restrictions arrives at a moment when semiconductor and component supply chains across Asia are already under strain from multiple rounds of policy intervention. Firms in South Korea, Taiwan, Japan, and Singapore have spent the past two years navigating overlapping and sometimes contradictory requirements from Washington, Brussels, and Beijing.
Optical transceiver suppliers in these markets now face the prospect of another bifurcation. If Chinese firms are cut off from US-origin components or denied access to US customers, regional players may be asked to fill the gap. That could mean windfall orders in the near term but also heightened scrutiny and pressure to enforce end-use restrictions on their own sales.
At the same time, Chinese domestic demand for AI infrastructure continues to grow. Local cloud operators and research institutions are building clusters that require the same high-speed interconnects. If export controls limit access to foreign modules, mainland suppliers may redirect output to the home market, potentially accelerating the development of a parallel, domestically anchored supply chain.
What Comes Next
No official policy announcement has been made. The US Department of Commerce has not published a proposed rule, and no formal interagency review timeline has been disclosed. The current market turbulence is driven entirely by anticipation and pattern recognition.
History suggests that when speculation reaches this intensity, some form of official guidance usually follows, whether to impose new restrictions, clarify existing rules, or explicitly exempt certain products. Until that guidance arrives, firms on both sides of the Pacific will continue to prepare for multiple scenarios, investors will continue to reprice risk, and supply-chain planners will continue to model contingencies they hope never to execute.