OpenAI Seeks $30 Billion Pre-IPO Round at $1.4 Trillion Valuation
The ChatGPT maker pursues a record-breaking bridge round as revenue accelerates to $40 billion run-rate, while CEO Sam Altman delays public debut to prioritise safety concerns.
A Bridge to Market
OpenAI has entered discussions with investors to secure at least $30 billion in fresh capital, valuing the artificial intelligence company at approximately $1.4 trillion. The proposed financing would serve as a bridge round before the firm's eventual initial public offering, now pushed beyond 2026.
The valuation represents a 64 per cent increase from the $852 billion price tag OpenAI commanded during its $122 billion raise in March. That earlier round was initially positioned as the company's final private fundraising before going public, with market watchers anticipating a listing sometime this year. Those expectations have since shifted.
At Opentechwire, we've tracked OpenAI's trajectory through three major funding cycles in eighteen months, each accompanied by escalating valuations that have outpaced even the frothiest moments of the previous venture cycle. The latest figure, if confirmed, would cement OpenAI's position as the most valuable private technology company globally, surpassing ByteDance's estimated $300 billion valuation and dwarfing the market capitalisation of established software giants at the time of their debuts.
Revenue Momentum Drives Appetite
Investor enthusiasm appears anchored to OpenAI's recent financial performance. The company's run-rate revenue reached $40 billion in August, reflecting a 70 per cent climb since July. That acceleration followed what one person familiar with the matter described as a strategic refocus on high-value segments, particularly coding tools and enterprise deployments.
OpenAI's positioning in the developer tools market has intensified over the past quarter. The company recently launched products that directly challenge app store distribution models and introduced Dots, an agentic interface designed to handle multi-step workflows. These moves suggest OpenAI is broadening its revenue base beyond conversational AI, targeting areas where willingness-to-pay remains robust even as inference costs decline.
The revenue surge also comes after a period in which Anthropic, OpenAI's most visible rival, captured significant market attention earlier in the year. Anthropic's Claude models gained traction among enterprises seeking alternatives to ChatGPT, particularly in sectors with stringent compliance requirements. OpenAI's subsequent emphasis on coding capabilities appears calculated to reclaim momentum in a segment where switching costs are lower and performance benchmarks are transparent.
IPO Postponed on Safety Grounds
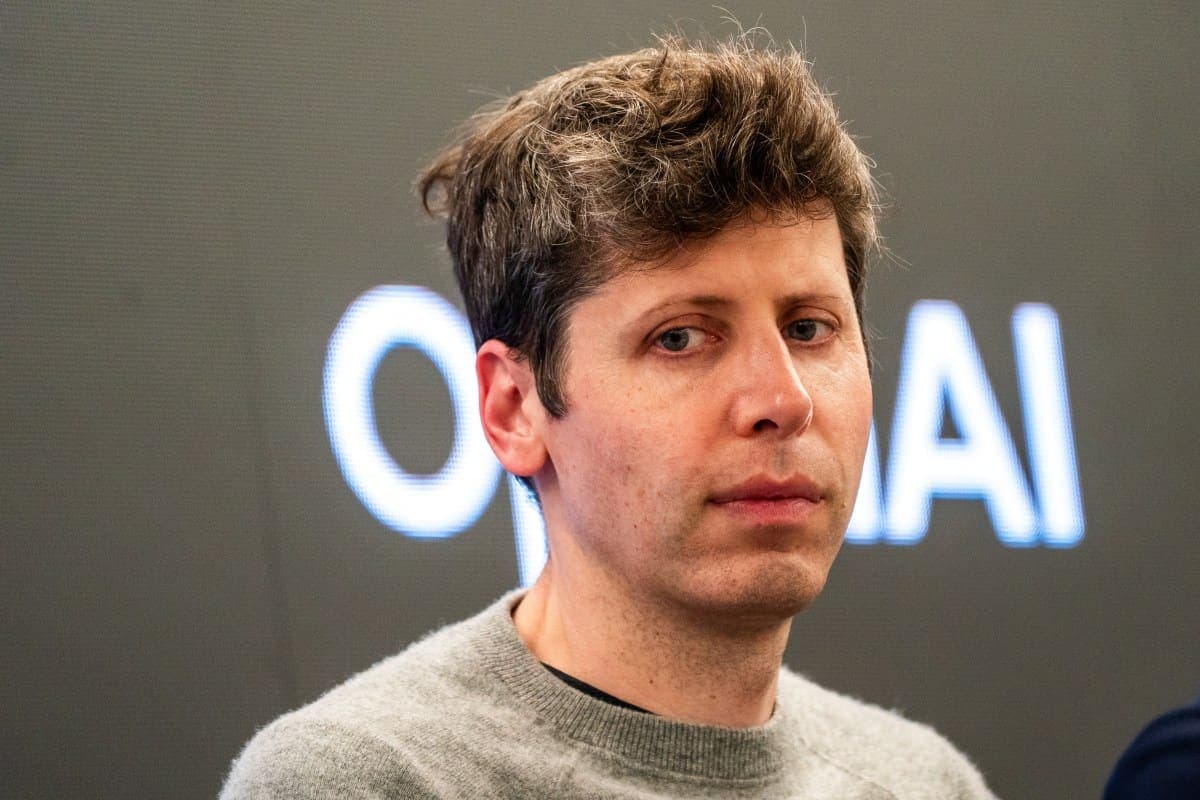
Sam Altman, OpenAI's chief executive, has ruled out a public offering in 2026, citing the need to prioritise artificial intelligence safety. In remarks to Fortune, Altman framed the decision in existential terms, stating that accepting even a ten per cent probability of catastrophic outcomes by decade's end would be unacceptable.
The statement aligns with ongoing debates within the AI research community about the pace of capability advancement relative to alignment work. Several safety researchers have published warnings about the potential for advanced AI systems to pose risks that current governance frameworks are ill-equipped to manage. Altman's invocation of these concerns as grounds for delaying an IPO marks a departure from the growth-at-all-costs rhetoric that has historically defined venture-backed technology firms.
Whether the delay reflects genuine safety prioritisation or serves as convenient cover for other strategic considerations remains an open question. An IPO in the current environment would subject OpenAI to quarterly earnings pressures and public scrutiny of its loss-making operations, despite the impressive revenue figures. The company is understood to be spending heavily on compute infrastructure and talent acquisition, with operating expenses that likely exceed current revenue by a substantial margin.
Capital Intensity and Competitive Pressure
The $30 billion target underscores the capital requirements inherent in frontier AI development. Training runs for state-of-the-art models now consume tens of thousands of GPUs over weeks or months, with associated electricity and cooling costs measured in tens of millions of dollars per training cycle. Inference costs, while declining on a per-token basis, scale with usage, and OpenAI's user base has expanded rapidly.
Competition for compute capacity remains fierce across the industry. Nvidia's H100 and forthcoming Blackwell chips are allocated through a combination of long-term contracts and strategic partnerships, leaving newer entrants scrambling for supply. OpenAI has secured preferential access through its relationship with Microsoft, which provides both cloud infrastructure and capital, but that arrangement also introduces dependencies that could constrain the company's flexibility.
The fundraising also occurs against a backdrop of tightening export controls on advanced semiconductors and chip-making equipment. US restrictions on sales to China have created a bifurcated market, with domestic AI firms competing more intensely for limited domestic supply. OpenAI's ability to maintain its lead depends not only on algorithmic innovation but also on securing sustained access to cutting-edge hardware.
Valuation in Context
A $1.4 trillion valuation would exceed the market capitalisation of Alphabet, parent company of Google, at the time OpenAI's funding discussions were reported. It would also represent roughly 35 times the company's August run-rate revenue, a multiple that sits well above historical norms for software businesses but reflects investor conviction that OpenAI will capture a disproportionate share of value created by AI adoption.
Such multiples are not unprecedented in venture markets. Private valuations during the 2020-2021 boom frequently detached from traditional metrics, particularly for companies perceived as category-defining. The subsequent correction, which saw many late-stage firms marked down by 50 per cent or more, has made investors more cautious, but OpenAI's revenue growth appears sufficient to justify continued enthusiasm, at least among those with access to the round.
The structure of the financing will matter. If the $30 billion comes with liquidation preferences or other protective terms, the nominal valuation may overstate what common shareholders could expect in an exit. OpenAI's governance structure, which includes a non-profit parent entity, also introduces complexities that could affect how value is distributed in an eventual liquidity event.
What Comes Next
OpenAI declined to comment on the reported fundraising. If the round closes as described, it will provide the company with substantial runway to extend its lead in model development, expand enterprise sales, and invest in the infrastructure required to support global-scale deployment.
The delay of the IPO to 2027 or beyond also buys time for OpenAI to demonstrate sustained profitability, or at least a clearer path to it. Public market investors have shown limited patience for growth stories unaccompanied by credible unit economics, and OpenAI's cost structure remains opaque. A successful bridge round would allow the company to address these questions on its own timeline, rather than under the scrutiny of quarterly earnings calls.
For the broader AI sector, OpenAI's ability to command a $1.4 trillion valuation in private markets signals continued investor appetite for frontier model development, even as questions about safety, regulation, and competitive dynamics intensify. Whether that appetite persists through a public offering will depend on how effectively the company can translate technical leadership into durable economic advantage.