Kazakhstan Charts Independent Path in AI Development Between US and China
Central Asian nation leverages its geographic position and energy resources to attract technology partnerships from both superpowers without committing to either camp
A Capital Caught Between Two Tech Spheres
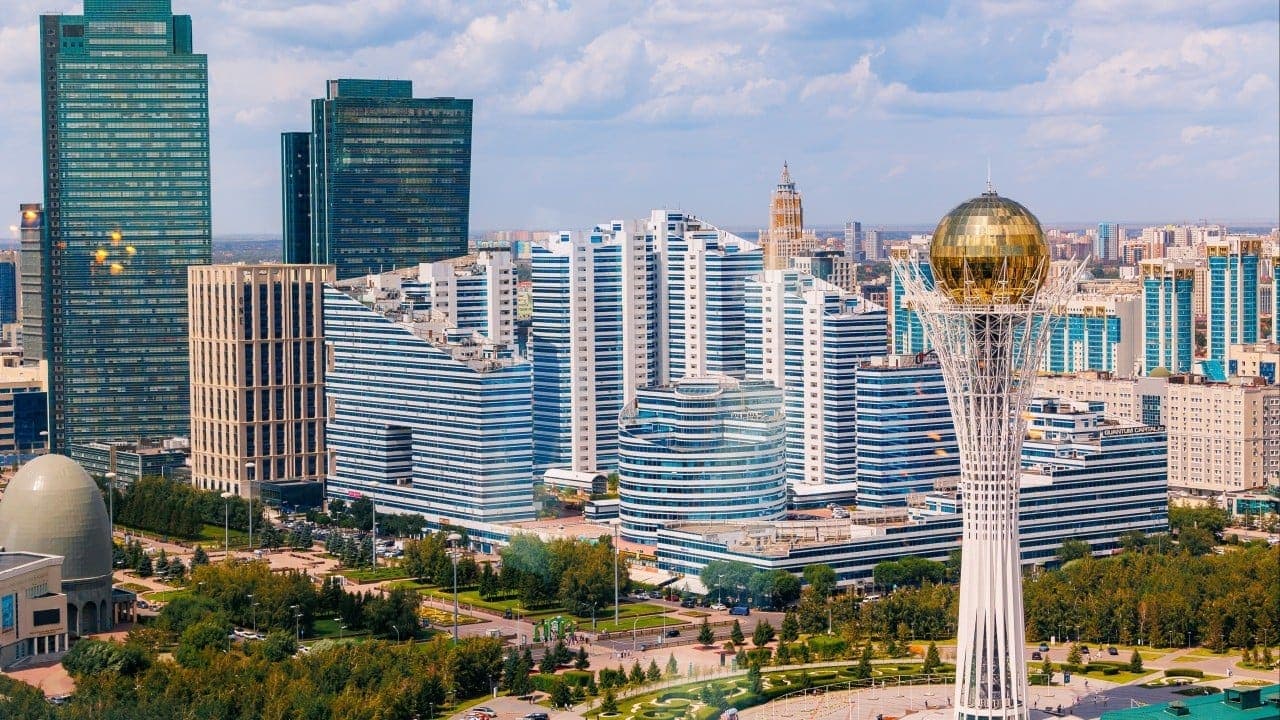
Chinese electric vehicles from BYD and Changan now fill the streets of Astana, displacing South Korean brands that dominated Kazakhstan's automotive market for years. Yet the shift in consumer preferences tells only part of the story unfolding across this energy-rich Central Asian nation. What matters more for the region's technology trajectory is happening behind closed doors in government ministries and data centre planning sessions.
Kazakhstan has emerged as an unlikely testing ground for whether a mid-sized economy can navigate the fractured technology landscape without choosing sides. The country is actively courting artificial intelligence infrastructure investment from both the United States and China, a balancing act that reflects broader questions about technology sovereignty in an era of intensifying export controls and supply chain bifurcation.
At Opentechwire, we've tracked similar dynamics across Southeast Asia and the Middle East, but Kazakhstan's approach stands out for its explicit refusal to commit. The country possesses advantages that give it leverage: abundant energy resources essential for power-hungry data centres, a geographic position linking Europe and Asia, and a government willing to experiment with regulatory frameworks that appeal to investors from multiple jurisdictions.
Energy Surplus Becomes Strategic Asset
Kazakhstan's pitch to technology investors centres on its electricity generation capacity. The country produces significantly more power than its domestic economy requires, primarily from coal and an expanding renewable portfolio. For companies building large-scale inference infrastructure or training clusters, electricity cost and reliability often matter more than proximity to end users.
Data centre operators we've followed across the region consistently cite energy as their primary site selection criterion, ahead of fibre connectivity or tax incentives. Kazakhstan's state-owned grid operator has signalled willingness to negotiate long-term power purchase agreements at rates competitive with traditional data centre hubs in northern Europe or the Pacific Northwest of the United States.
The energy advantage also insulates Kazakhstan from some of the geopolitical pressure facing nations more dependent on foreign investment for basic infrastructure. A country that can credibly threaten to redirect power capacity elsewhere holds more negotiating room than one desperate for any investment it can attract.
Regulatory Flexibility as Competitive Edge
Kazakhstan's government has drafted artificial intelligence policy frameworks designed to accommodate both Chinese and US technology stacks. This requires careful technical and legal engineering. American cloud providers typically demand data residency guarantees and compliance structures that align with US export control regulations. Chinese firms often seek different concessions around data flows and operational autonomy.
Rather than choosing one standard, Kazakh regulators are creating parallel approval pathways. Foreign investors can select which compliance regime to follow based on their origin jurisdiction and technology partnerships. This modular approach mirrors strategies we've observed in the United Arab Emirates and Singapore, though those financial hubs possess deeper institutional capacity.
The risk is that maintaining dual systems becomes administratively unworkable or that one power eventually pressures Kazakhstan to close off the competing pathway. Export controls on advanced chips already limit which AI systems can legally be deployed in Kazakhstan under US rules. If Washington tightens those restrictions or Beijing imposes reciprocal requirements, the neutral positioning becomes harder to sustain.
Chinese Hardware, American Software
In practice, Kazakhstan's technology landscape already reflects a hybrid model. Chinese telecommunications equipment underpins much of the country's network infrastructure, installed over the past fifteen years as Huawei and ZTE competed aggressively across Central Asia. Consumer electronics and vehicles from Chinese manufacturers have captured market share through competitive pricing and financing arrangements.
Yet Kazakhstan's financial sector, government agencies, and larger enterprises often run software and cloud services from US providers or European vendors. English remains the dominant language for technical documentation and developer training. The country's small but growing community of AI researchers and engineers typically train on frameworks and tools originating from American technology companies.
This separation between hardware and software layers is common across emerging markets, but it creates dependencies that complicate the neutral stance. A data centre built with Chinese servers running US cloud software sits at the intersection of two supply chains that are actively decoupling. Any future export restriction or sanctions regime could render such facilities inoperable or force uncomfortable choices about which components to replace.
The Limits of Strategic Ambiguity
Kazakhstan's approach works as long as both the United States and China see value in competing for influence rather than demanding exclusivity. That calculus could shift. American policymakers have shown increasing willingness to use technology access as a foreign policy lever, particularly around artificial intelligence and semiconductor equipment. The CHIPS Act and subsequent export control measures signal that Washington views technology leadership as a zero-sum competition.
China has generally taken a more transactional approach in Central Asia, emphasising infrastructure investment and trade relationships over ideological alignment. But that posture could harden if Beijing perceives Kazakhstan tilting too far toward Western technology standards or security partnerships.
The country also faces internal constraints. Kazakhstan's domestic AI talent pool remains thin, and its research institutions lack the funding and international connections of universities in neighbouring Russia or major Asian technology hubs. Attracting foreign investment in data centres does not automatically translate into local capability development or technology transfer.
Regional Template or Isolated Case
Whether Kazakhstan's balancing strategy proves sustainable matters beyond its borders. Several Central Asian nations face similar decisions about technology partnerships and infrastructure investment. Uzbekistan, Kyrgyzstan, and Tajikistan all sit along digital corridors linking China to Europe and the Middle East.
If Kazakhstan successfully maintains relationships with both technology blocs while building out AI infrastructure, it provides a template for other non-aligned nations seeking to avoid dependency on a single supplier. If the model collapses under geopolitical pressure or proves economically unviable, it reinforces the argument that countries must ultimately choose sides in a bifurcated technology world.
The next eighteen months will clarify which outcome is more likely. Major data centre projects currently in planning stages will either proceed with mixed funding sources and technology stacks, or investors will demand exclusivity provisions that force clearer alignment. Export control regimes will either stabilise at current levels or tighten further, narrowing the window for neutral positioning.
For now, Kazakhstan is making a calculated wager that its energy resources and geographic position give it enough leverage to resist pressure from both directions. The country's willingness to experiment with dual regulatory frameworks and hybrid technology infrastructure reflects pragmatism born of limited alternatives. Whether pragmatism proves sufficient depends on forces largely outside Astana's control.