Japan's Semiconductor Exports Surge on AI Infrastructure Demand
Memory chip shipments climbed 41 per cent in six months as data centre buildout drives prices to multi-year highs
A Fiscal Tailwind from Silicon
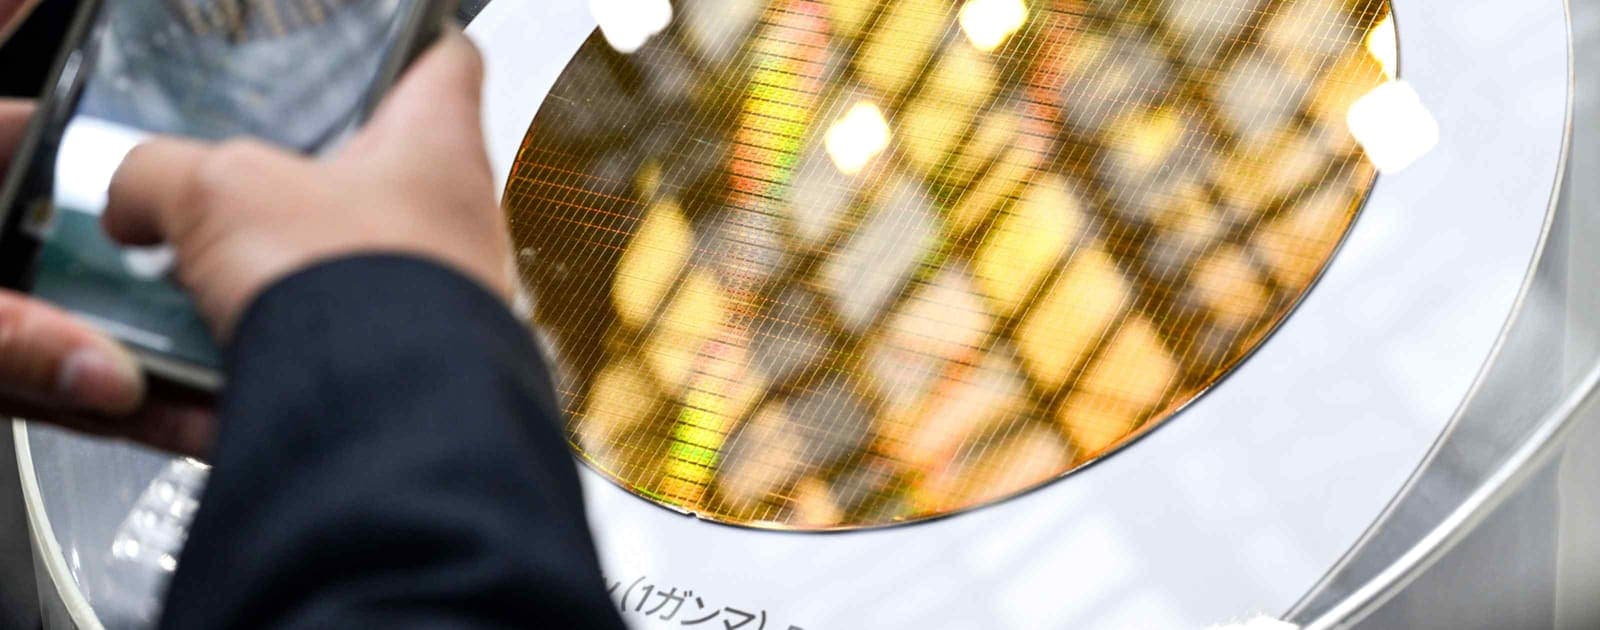
Between April and September 2026, Japan shipped chip-related products worth 41 per cent more than the same period a year earlier, a sharp acceleration that reflects how quickly AI infrastructure spending has reshaped global semiconductor flows. The Ministry of Finance trade data, released at the end of October, shows export prices for certain memory products climbing roughly fivefold year-on-year, a rate of appreciation rarely seen outside supply crises or major technology transitions.
At Opentechwire, we've tracked similar jumps in Korea and Taiwan over the past eighteen months, but Japan's trajectory stands out for two reasons: the speed at which legacy DRAM and NAND lines have been repurposed for high-bandwidth applications, and the degree to which this revenue spike is cushioning a wider trade deficit driven by elevated crude oil costs. Semiconductor demand, in other words, is doing more than padding manufacturer balance sheets. It is acting as a macroeconomic stabiliser in an economy still heavily reliant on energy imports.
Memory Prices and the AI Multiplier
The price surge centres on DRAM and NAND flash, both of which have seen contract and spot quotations rise sharply since early 2025. Hyperscale data centre operators building out GPU clusters require not only cutting-edge high-bandwidth memory, but also vast quantities of conventional DRAM for server nodes and NAND for nearline storage arrays. That dual demand has tightened supply across the board, even for older-generation products that were, until recently, trading near cash-cost floors.
Japanese manufacturers, led by Kioxia in NAND and a handful of smaller DRAM packaging and test houses, have benefited disproportionately. Kioxia's Yokkaichi and Kitakami fabs have been running at or near capacity, and the company has prioritised high-margin enterprise SSD and data centre module shipments over consumer products. The result is a revenue mix that amplifies any uptick in average selling prices.
What makes the current cycle unusual is its persistence. Previous memory rallies, driven by smartphone launches or PC refresh cycles, typically lasted two to three quarters before inventory corrections set in. The AI infrastructure buildout, by contrast, is entering its third year with no clear peak in sight. Hyperscalers continue to place orders eighteen to twenty-four months out, a planning horizon that provides memory makers with the confidence to restart mothballed capacity and negotiate long-term supply agreements.
Trade Balance Implications
Japan's overall trade position remains in deficit, a structural feature that has deepened since the yen's depreciation and the post-pandemic rebound in energy prices. Crude oil and liquefied natural gas account for a large share of import value, and while the yen has stabilised somewhat in recent months, the nominal cost of energy remains elevated relative to the 2010s.
Semiconductor exports, however, are now large enough to offset a meaningful portion of that deficit. In the April to September period, chip-related shipments contributed an estimated incremental ¥1.8 trillion in export value compared to the prior year, equivalent to roughly half the trade deficit recorded over the same six months. That shift matters not only for headline trade statistics but also for industrial policy debates within the Ministry of Economy, Trade and Industry, where officials have been weighing the merits of further subsidies for domestic fab construction against the fiscal cost of such programmes.
The argument for continued support has grown easier to make. If semiconductor exports can reliably dampen trade volatility, the strategic case for maintaining and expanding domestic production capacity strengthens, even if individual projects carry high upfront capital costs and uncertain returns. This logic underpins recent announcements around joint ventures with TSMC and increased funding for equipment suppliers like Tokyo Electron, which itself reported record order backlogs in October.
Risks in the Revenue Stream
Sustainability is the open question. Memory markets are famously cyclical, and the current rally has already outlasted most historical precedents. Several factors could trigger a correction: a slowdown in hyperscale capex if AI model training efficiency improves faster than expected; geopolitical disruption to supply chains, particularly those linking Japan, South Korea and Taiwan; or a glut of new capacity coming online in China, where local NAND producers have been ramping output with the help of state-backed financing.
Chinese competition is particularly salient for Kioxia. The company's market capitalisation has fallen by roughly two-thirds from its peak, in part because investors anticipate margin compression as Yangtze Memory Technologies and other mainland manufacturers scale up. Those firms operate under different cost structures and face fewer quarterly earnings pressures, allowing them to underprice Japanese and Korean rivals when necessary. If AI demand plateaus and the market shifts back toward price competition, Japan's current export windfall could reverse quickly.
There is also the question of product mix. High-bandwidth memory, the premium segment driving much of the recent margin expansion, is dominated by SK Hynix and Samsung. Japanese suppliers play a supporting role through materials, equipment and packaging, but they do not capture the same per-unit economics. If the next phase of AI infrastructure leans even more heavily toward HBM3E and future generations, Japan's position in the value chain may shift from principal supplier to ancillary vendor, with corresponding implications for export revenue.
Policy and Industrial Strategy
The semiconductor surge has arrived at a moment when Tokyo is finalising a medium-term growth strategy that places chips at the centre of near-term industrial policy and AI at the centre of medium-term ambitions. The overlap is deliberate: chips are the enabler, AI the application, and the government's role is to ensure that Japanese firms capture value at both layers.
Execution, however, remains uneven. Subsidy programmes have successfully attracted foreign investment, most visibly TSMC's Kumamoto fab, but domestic champions like Kioxia face ongoing challenges around capital structure, governance and strategic direction. The company's planned relisting, which would provide an exit for Bain Capital and other private equity investors, has been delayed multiple times, and uncertainty around the IPO has complicated long-term capacity planning.
Meanwhile, equipment makers like Tokyo Electron are thriving, buoyed by global demand for deposition, etch and lithography tools. The divergence between equipment suppliers and device manufacturers reflects a broader reality: Japan's comparative advantage in semiconductors today lies more in the tools and materials that enable production than in the chips themselves. That is not a weakness, but it does require a different policy approach, one focused on sustaining R&D leadership in narrow technical domains rather than attempting to rebuild integrated device manufacturing at scale.
What the Data Tells Us
The 41 per cent export increase is impressive, but it should be read as a snapshot of a particular moment, not a new baseline. Memory prices have peaked before, and they will peak again. What matters for Japan's semiconductor industry is whether the current cycle provides enough breathing room to restructure, consolidate and invest in next-generation technologies that can sustain competitiveness beyond the AI boom.
So far, the evidence is mixed. Revenue is up, capacity utilisation is high, and the trade balance has improved. But the structural challenges, particularly around Chinese competition and the shift toward HBM, have not been resolved. The next twelve months will reveal whether Japan's chipmakers can convert a cyclical windfall into a durable strategic position, or whether the current surge will be remembered as a brief interlude before the next downturn.