Grab Bets $1.49 Billion on Buy-Now-Pay-Later to Deepen Southeast Asia Lending
The Singapore super-app operator is acquiring a majority stake in Atome Financial, signalling a shift from transport logistics to consumer credit as its next growth vector.
A Super-App Recalibrates Its Financial Ambitions
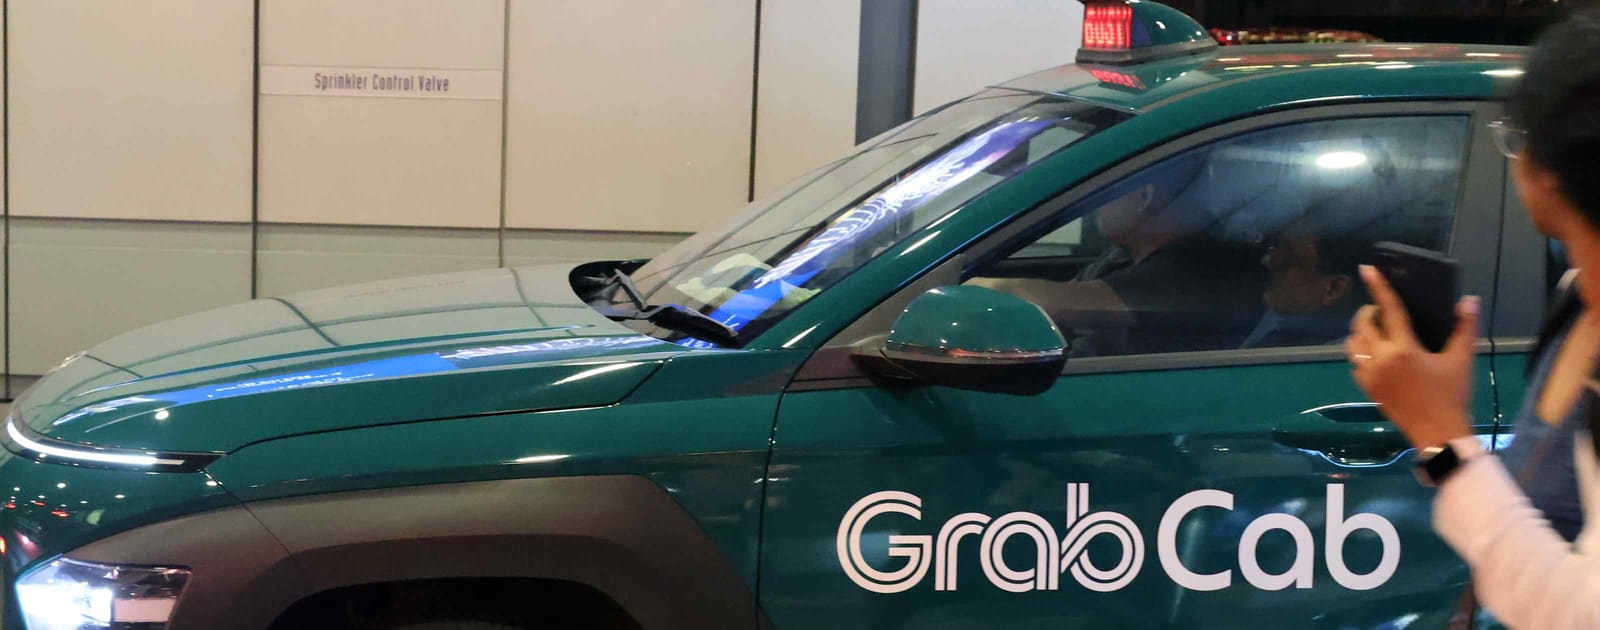
Grab announced on 15 September that it will acquire a 60 per cent stake in Atome Financial, a Singapore-based buy-now-pay-later provider, for $1.49 billion. The transaction represents the ride-hailing operator's most substantial fintech acquisition to date and signals a strategic pivot towards consumer lending infrastructure across Southeast Asia.
The deal will fold Atome's instalment payment technology and merchant network into Grab's existing financial services arm, which already operates a digital bank and provides loans to drivers and small merchants. For Grab, the rationale is straightforward: its ride-hailing and food-delivery platforms generate millions of daily transactions, but monetisation per user remains shallow. Consumer credit offers a higher-margin channel to deepen engagement with the same customer base.
At Opentechwire, we have tracked the quiet build-out of fintech capabilities inside Southeast Asia's super-apps over the past three years. What began as wallet features and driver advances has matured into full-stack financial services. Grab's move to acquire rather than build a BNPL product suggests urgency; the region's instalment credit market is fragmenting quickly, and first-mover advantages in merchant integration matter.
The Atome Asset and Its Regional Footprint
Atome Financial operates across eight markets in Asia, including Singapore, Malaysia, Indonesia, Hong Kong, and Taiwan. The platform allows consumers to split purchases into interest-free instalments at checkout, funded by merchant discount fees. Atome has built partnerships with online and offline retailers, from e-commerce platforms to electronics chains and fashion outlets.
The company's value to Grab lies in two areas: an established merchant network that can be cross-sold Grab's delivery and advertising products, and a credit-scoring engine trained on Southeast Asian transaction patterns. Traditional banks in the region remain cautious in underwriting unsecured consumer loans, particularly for younger earners without credit histories. BNPL providers have filled that gap by using alternative data, real-time transaction monitoring, and lower ticket sizes to manage risk.
Grab has not disclosed Atome's revenue or loan book size, but the $1.49 billion valuation for a 60 per cent stake implies an enterprise value near $2.5 billion. That places Atome among the more expensive BNPL acquisitions in Asia, especially given the sector's recent contraction in public market valuations. The premium suggests Grab sees strategic rather than purely financial value in the asset.
Why Consumer Lending Matters for Grab's Unit Economics
Grab's core businesses, ride-hailing and food delivery, are operationally mature but margin-constrained. Both require continuous subsidies to retain drivers and consumers, and regulatory pressure on commission rates has intensified across the region. Financial services, by contrast, generate revenue without the variable costs of physical logistics.
The company's digital bank, launched in Singapore in partnership with Singtel, has focused on savings accounts and corporate lending. Adding a consumer credit layer allows Grab to capture a different segment: frequent platform users who want to smooth payments over time. If a customer books a ride, orders food, and splits a grocery bill into instalments, Grab touches three revenue streams from a single relationship.
Grab has also lifted its 2028 financial targets, according to the announcement, though specific figures were not provided. The guidance revision suggests management expects Atome's contribution to accelerate both revenue growth and adjusted EBITDA margins. That confidence may be warranted if integration costs are contained and Atome's existing loan performance holds steady.
Regional BNPL Dynamics and Competitive Pressure
Southeast Asia's BNPL market has grown rapidly, but it remains fragmented. Local players like Atome compete with global entrants, e-commerce-embedded instalment products from Shopee and Lazada, and bank-issued instalment plans. Regulation is tightening: Singapore's central bank has proposed affordability checks for BNPL users, and Indonesia is considering licensing requirements that would raise compliance costs.
Grab's scale offers a potential moat. The company operates across multiple verticals, which means it can offer merchants bundled services: delivery logistics, advertising, and now instalment credit. A restaurant or retailer already using GrabFood or GrabMart may find it simpler to adopt Atome's payment option if it is integrated into the same dashboard.
However, consumer credit carries execution risk. Default rates on unsecured instalment loans have climbed in several Southeast Asian markets as pandemic-era savings deplete and inflation pressures household budgets. Grab will need to manage credit quality carefully, particularly if it extends Atome's offering to lower-income users who currently rely on cash or remittances.
What the Acquisition Reveals About Super-App Strategy
The Atome deal underscores a broader shift in how Southeast Asia's super-apps are thinking about growth. Early-stage super-apps competed on breadth, adding services to maximise time spent in-app. The next phase is about depth: extracting more revenue per user by layering financial products onto existing behaviours.
Grab is not alone in this approach. GoTo in Indonesia has expanded its fintech arm aggressively, and Sea's SeaMoney has scaled digital wallets and lending across the region. The prize is the same: a larger share of consumer spending, captured through credit rather than commerce alone.
For Grab, the acquisition also addresses a strategic vulnerability. Its digital bank has grown slowly, constrained by regulatory capital requirements and conservative underwriting. Atome offers a faster path to consumer lending scale, with a lighter regulatory footprint than deposit-taking banking. If the integration succeeds, Grab will have assembled a financial services stack that spans payments, savings, corporate loans, and consumer credit, all within a single app used by tens of millions weekly.
Open Questions on Integration and Returns
The challenge now is execution. Integrating Atome's technology, compliance frameworks, and merchant relationships into Grab's platform will require coordination across multiple jurisdictions, each with distinct regulations on consumer lending, data privacy, and cross-border payments. Grab's track record on acquisitions is mixed; past integrations have taken longer and cost more than initially projected.
There is also the question of whether BNPL economics will hold as the sector matures. Merchant discount rates are under pressure, and consumers are becoming more selective about which instalment offers they accept. If Grab cannot cross-sell effectively or if default rates rise, the $1.49 billion outlay may weigh on returns.
Still, the deal reflects a calculated bet that Southeast Asia's consumer credit market is undersupplied and that the winner will be the platform with the most frequent customer touchpoints. Grab has those touchpoints. Whether it can convert them into durable lending relationships will determine whether this acquisition reshapes its business model or becomes a costly detour.