E-Commerce Platforms Drive Southeast Asia's Digital Growth as AI Monetisation Lags
The region's digital economy is set to reach $368 billion in 2026, powered by AI-enhanced product recommendations and content tools, even as direct revenue from the technology remains elusive.
AI Embeds Itself Without a Clear Revenue Model
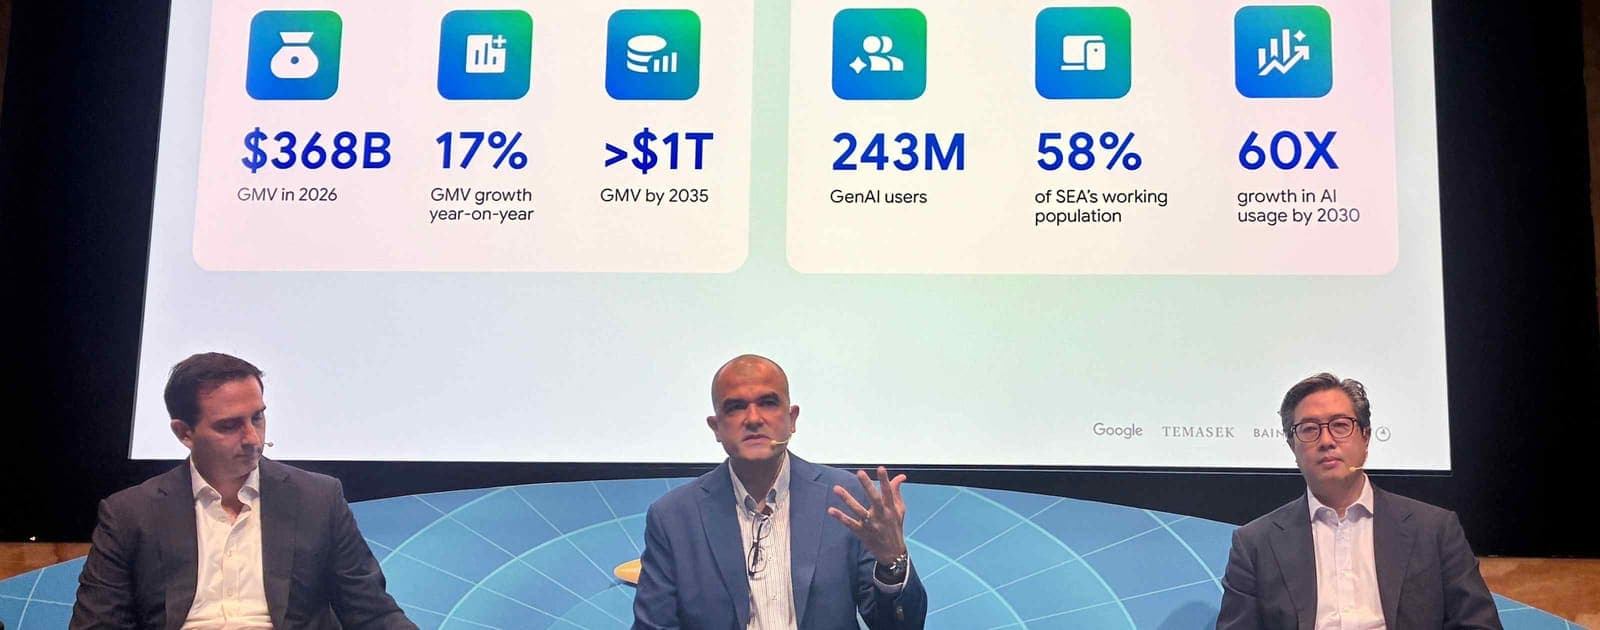
Southeast Asia's digital economy is on track to reach $368 billion in 2026, according to new research presented in Singapore on 21 October by Bain & Company, Google and Temasek Holdings. The figure reflects sustained expansion even as global economic headwinds persist, but the report underscores a striking paradox: artificial intelligence is reshaping the region's e-commerce landscape whilst generating almost no direct revenue for the companies deploying it.
At Opentechwire, we have tracked the adoption curve of machine learning across the region's platforms for the past three years, and the gap between usage and monetisation has widened rather than closed. Product recommendation engines, dynamic pricing algorithms and generative tools for listing copy now underpin the operations of nearly every major marketplace from Jakarta to Manila. Yet the infrastructure providers, model developers and API vendors that enable this capability have struggled to translate deployment into sustainable income streams.
The disconnect is not unique to Southeast Asia, but the region's price-sensitive consumer base and thin operating margins make it an especially harsh testing ground for AI economics. Where Western platforms can absorb experimentation costs or bundle AI features into premium tiers, Southeast Asian operators face a user cohort that expects sophistication at zero incremental cost.
E-Commerce Absorbs the Heaviest AI Load
The report singles out e-commerce as the sector experiencing the most pronounced AI integration. Recommendation engines now account for a material share of gross merchandise value on leading platforms, routing users toward products they are statistically more likely to purchase. Content generation tools, meanwhile, allow small merchants to produce listing descriptions, images and promotional copy without hiring external agencies or dedicating internal resources.
These capabilities have measurably improved conversion rates and average order values, according to platform operators Opentechwire has spoken with over the past year. Yet the AI vendors supplying the underlying models report that contracts remain heavily discounted, structured as proof-of-concept arrangements or tied to revenue-share clauses that rarely trigger meaningful payouts.
The challenge is compounded by the region's fragmented regulatory environment. Thailand, Vietnam and Indonesia have each introduced data localisation requirements that force model providers to replicate infrastructure across borders, raising capital expenditure without a corresponding increase in contract value. Singapore's more permissive framework has attracted investment, but the city-state's small domestic market limits the scalability of any single deployment.
Private Capital Floods Infrastructure, Not Applications
One bright spot in the report is the surge in private funding for digital infrastructure. Data centre construction, subsea cable projects and edge computing nodes have attracted significant commitments from both regional and international investors. This capital flow reflects confidence in long-term demand, but it also highlights a structural imbalance: infrastructure scales more predictably than the applications meant to run on it.
AI workloads require low-latency, high-throughput environments, and Southeast Asia's archipelagic geography makes that expensive to deliver. The result is a race to build capacity ahead of proven use cases, a pattern that has historically led to overcapacity and write-downs in other technology cycles. The current wave of investment assumes that monetisation models will eventually catch up to deployment, but the report offers little evidence that inflection point is near.
At the same time, the infrastructure build-out creates a favourable environment for experimentation. Startups and established platforms alike can access compute resources at declining unit costs, which lowers the barrier to testing new AI features. The risk is that this abundance encourages feature proliferation without business discipline, further delaying the emergence of sustainable revenue models.
Consumer Expectations Outpace Willingness to Pay
Southeast Asian consumers have grown accustomed to AI-enhanced experiences, from personalised product feeds to chatbot support, but surveys consistently show minimal willingness to pay for these features directly. The expectation is that platforms will absorb the cost as part of their competitive differentiation, a stance that leaves little room for AI vendors to capture value.
This dynamic is most visible in the ride-hailing and food delivery segments, where AI optimises dispatch, routing and pricing in real time. Users benefit from faster service and lower wait times, yet any attempt to introduce an AI surcharge or premium tier has met with resistance. The platforms themselves operate on razor-thin margins, leaving scant budget to compensate the technology providers whose models power the optimisation.
The situation is further complicated by the prevalence of super-app architectures. A single platform may bundle e-commerce, payments, logistics and media, all of which rely on shared AI infrastructure. Allocating costs and attributing value across these verticals is a non-trivial accounting exercise, and it often results in AI being treated as a sunk cost rather than a line item with its own return expectations.
Policy and Talent Gaps Slow Maturation
Regulatory clarity remains patchy across ASEAN member states. Some governments have introduced AI ethics guidelines or data protection frameworks, but enforcement is inconsistent and cross-border coordination is minimal. This uncertainty discourages long-term investment in localised AI products, as vendors cannot predict whether today's compliant system will remain so under tomorrow's rules.
Talent supply is another constraint. The region produces a growing number of computer science graduates, but specialisation in machine learning, natural language processing and reinforcement learning lags behind demand. Salaries for experienced AI engineers in Singapore and Kuala Lumpur have climbed steeply, eroding the cost advantage that once made the region attractive for technology development. Smaller markets struggle to retain talent altogether, as engineers migrate to hubs with more robust ecosystems and higher compensation.
Training programmes and university partnerships have proliferated, but the pipeline from education to deployment remains slow. By the time a cohort of graduates enters the workforce, the tools and frameworks they learned may already be obsolete, requiring continuous upskilling that few employers are equipped to provide at scale.
What Comes Next for Regional AI Economics
The trajectory of Southeast Asia's digital economy over the next several years will hinge on whether monetisation models can catch up to deployment. The infrastructure is being built, the use cases are proliferating and the user base is engaged. What remains missing is a pricing mechanism that allows AI providers to capture a share of the value they create without alienating cost-conscious consumers or margin-stretched platforms.
One potential pathway is enterprise adoption. Large conglomerates in manufacturing, logistics and financial services have begun piloting AI tools for internal operations, and these buyers are accustomed to paying for software on a per-seat or per-transaction basis. If these deployments prove out, they could provide the revenue stability that consumer-facing applications have not.
Another possibility is consolidation. As platforms scale and competition narrows, the survivors may gain enough pricing power to pass AI costs through to users or negotiate better terms with technology vendors. This would accelerate monetisation but could also reduce innovation, as smaller players exit the market.
For now, the region's digital economy continues to grow on the strength of AI-enhanced experiences that no one is quite sure how to pay for. It is a precarious equilibrium, but one that reflects the broader global uncertainty around the economics of artificial intelligence. Southeast Asia is neither ahead nor behind in solving this puzzle; it is simply navigating the same contradictions at a different scale and with fewer resources to cushion the inevitable missteps.