ASML's China Revenue Doubles as Washington's Equipment Clampdown Backfires
The Dutch lithography leader now expects Beijing-linked sales to hit 20 per cent of annual revenue, underlining how export controls accelerate stockpiling instead of slowing capacity.
A Surge That Defies the Squeeze
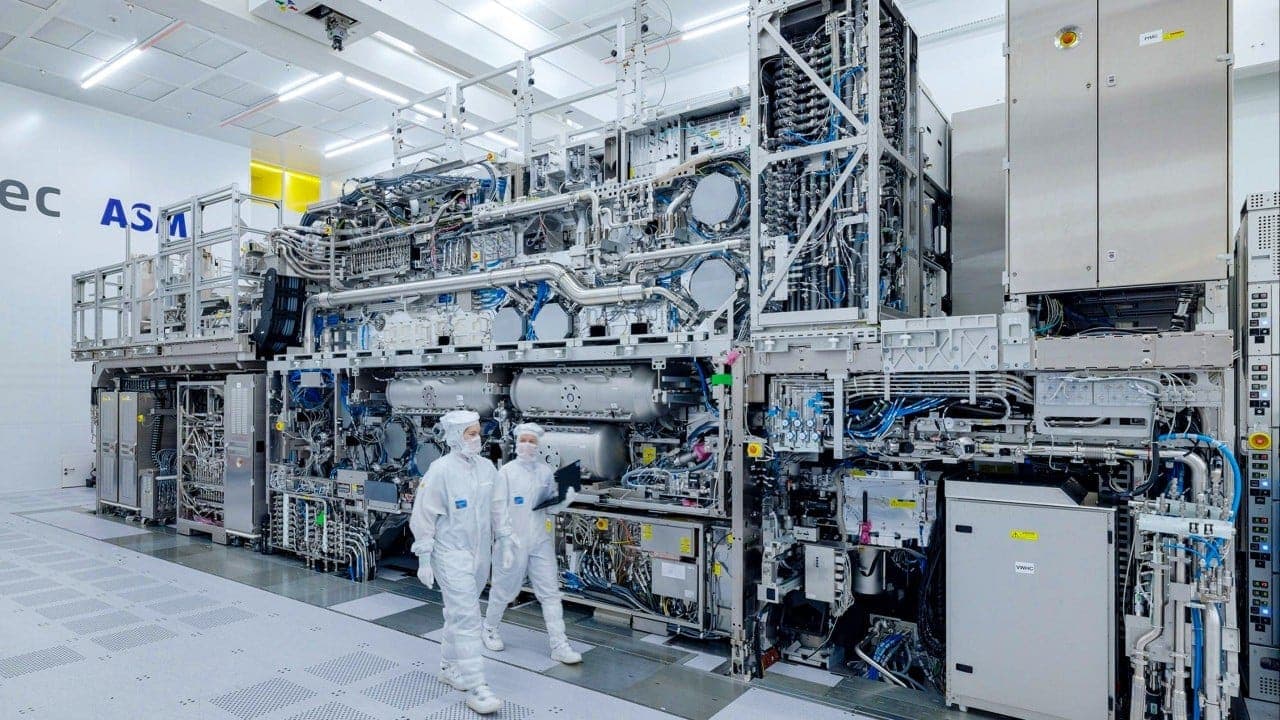
ASML's China business grew 109 per cent quarter-on-quarter in the three months to September, the Dutch lithography monopolist disclosed this week, lifting the mainland's projected share of full-year revenue to approximately one-fifth. The jump arrives against a backdrop of intensifying Washington pressure on The Hague to tighten export licensing for deep-ultraviolet (DUV) steppers - older-generation tools that remain the workhorse of most logic and memory fabs outside the leading edge.
The Veldhoven-based firm has long been the sole supplier of extreme-ultraviolet (EUV) systems, already banned from China under a 2019 Dutch export rule aligned with the Wassenaar Arrangement. What is accelerating now is demand for the previous-generation DUV platform - immersion and dry ArF scanners capable of patterning nodes from 7 nanometres down to 28 nanometres when combined with multi-patterning. Chinese foundries, memory makers and integrated-device manufacturers have been placing orders at a pace that suggests less a measured capacity expansion than a race to secure inventory before the regulatory window closes.
At Opentechwire, we have tracked similar front-loading behaviour in other categories - NVIDIA's A800 adapters, Applied Materials etch chambers, Lam Research deposition tools - each time a rule tightens or a licence review begins. The result is a temporary revenue windfall for the OEM, a permanent installed base inside China, and negligible impact on the capability those tools deliver once they are in production.
The DUV Bottleneck That Isn't
DUV immersion lithography can, with sufficient process layering, achieve geometries well into the single-digit nanometre range. SMIC's 7-nanometre radio-frequency chip, reverse-engineered from a Huawei handset in 2023, relied on exactly this approach: ASML's NXT:2000i or similar platforms running dozens of exposures per critical layer. Yield is lower and cycle time longer than an EUV-printed equivalent, but the physics works and the economics pencil when the alternative is no domestic supply.
Washington's 2022 export rule, updated last October, introduced a new performance threshold that would capture some high-numerical-aperture DUV immersion tools. The Dutch government has yet to codify that standard into its own licensing regime, leaving a grey zone that ASML's order book has evidently exploited. Meanwhile, China's national semiconductor fund - now in its third capitalisation round - continues to direct subsidies toward equipment procurement, creating a buy-now dynamic that overwhelms any marginal price increase from compliance overhead.
The strategic irony is that every delivered tool extends the runway for indigenous process development. Once installed, an NXT-series scanner has an operational lifespan of fifteen to twenty years with proper maintenance, and ASML's service contracts ensure uptime remains above 95 per cent even under export-license restrictions on spare parts. The policy has thus converted a flow problem - ongoing access - into a stock problem - entrenched capability.
Policy Lag and the Front-Running Cycle
US officials have reportedly been urging the Netherlands to adopt a shipment cap or a hard cutoff date for immersion tools destined for Chinese customers. Those conversations have been ongoing since mid-2025, yet no formal measure has been published. The delay has created a window during which Chinese buyers can lock in allocations, and ASML's guidance implies those commitments will be recognised as revenue through the fourth quarter and into early next year.
This is the third iteration of the same pattern. When the first Entity List additions hit Huawei in 2019, semiconductor toolmakers saw a spike in orders from alternative Chinese buyers. When the October 2022 rule targeted advanced logic and memory, orders shifted toward mature-node equipment. Now, as the definition of "advanced" creeps downward, the scramble has moved to the highest-performance DUV systems still technically permissible.
Export-control scholars have a term for this: the announcement effect. The moment a restriction is signalled, it triggers a procurement surge that front-runs the implementation date. If the goal is to limit cumulative installed capacity, the signalling itself undermines the objective.
ASML's Balancing Act
For ASML, China remains both a margin tailwind and a geopolitical tightrope. The company has no EUV exposure in the market - those systems are unambiguously blocked - but DUV represents roughly 60 per cent of unit shipments and a lower but still significant share of revenue. Losing unfettered access to Chinese customers would require either new end-markets or a structural reset of the cost base.
Management has been careful to frame the current strength as a function of "industry-wide capacity investment" rather than anticipatory buying, but the quarterly cadence tells a different story. Sequential growth of 109 per cent is not organic; it is transactional urgency. The company's full-year China guidance - 20 per cent of total sales - would place the market on par with South Korea and ahead of Japan, despite the latter two hosting some of the world's most advanced fabs.
The revenue is welcome in a quarter when ASML's overall backlog has moderated, but it comes with a compliance cost. The firm must navigate Dutch, US and - increasingly - European Union dual-use regulations, any of which can retroactively reclassify a tool or customer. Each shipment carries reputational risk if the end-use later proves to be military-adjacent or if the process node achieved exceeds what the export licence anticipated.
What the Numbers Tell Us About Decoupling
If the objective of multilateral export controls is to decouple China from the leading edge of semiconductor manufacturing, the ASML data suggests the policy is succeeding - but only at the margin it explicitly targets. EUV remains out of reach, which imposes a ceiling on single-exposure resolution and, by extension, on power efficiency and transistor density at 5 nanometres and below. But everything above that threshold - 7-nanometre radio-frequency, 14-nanometre automotive compute, 28-nanometre power management, 40-nanometre microcontrollers - remains accessible with the installed DUV base.
The volume of that base is now growing faster than it is depreciating. ASML's third-quarter shipments alone likely added fifteen to twenty immersion-capable systems to Chinese fabs, each of which can support multiple process layers across dozens of products. Multiplied across other equipment vendors - Tokyo Electron, Lam, Applied Materials, KLA - the cumulative toolset now in place is sufficient to serve the majority of the semiconductor market by unit volume, if not by headline node.
China's share of global fab capacity, measured by installed wafer starts per month, has risen from 16 per cent in 2020 to an estimated 24 per cent in 2026, according to SEMI data. Much of that growth sits in the 28-nanometre to 65-nanometre range, precisely where DUV tools dominate and where export controls have the least bite. The technology frontier has been constrained; the manufacturing base has not.
The Service and Spare-Parts Question
One underappreciated dimension of the ASML relationship is the post-sale service obligation. Lithography tools are not turnkey appliances; they require quarterly calibration, consumable replacement - lasers, lenses, reticle stages - and software updates that tune overlay accuracy and throughput. ASML's field-service engineers have historically made regular visits to Chinese customer sites, and the company's remote diagnostic platform provides real-time uptime monitoring.
US export rules have introduced restrictions on the provision of service and spares for certain tools installed at Entity List facilities. But enforcement is inconsistent, and ASML has argued that denying service to an already-delivered tool constitutes an ex-post rule change that violates Dutch legal principles. The practical result is that most systems continue to receive support, which sustains their operational value and extends their effective lifespan well beyond the original sale date.
If future restrictions do sever the service link, Chinese fabs will face a choice: reverse-engineer the consumables and calibration routines, or accept a gradual degradation in yield and throughput. The former is difficult but not impossible - China's domestic equipment ecosystem has demonstrated the ability to clone older-generation platforms with a two-to-three-year lag. The latter is a cost, but one that can be absorbed if the alternative is zero domestic production.
What Comes Next
ASML's guidance implies the China revenue share will moderate in 2027, assuming no further acceleration in orders and some implementation of the mooted Dutch restrictions. But the installed base will remain, and its utilisation will rise as Chinese IDMs and foundries ramp production to meet domestic demand and, increasingly, to target export markets in automotive, industrial and consumer electronics.
The policy debate in Washington and Brussels is now shifting toward a second layer: not just what tools can be sold, but what end-products can be made with them. The US Department of Commerce has floated the idea of "positive lists" - approved use-cases for controlled equipment - and the European Union is exploring supply-chain due-diligence rules that would require disclosure of manufacturing provenance. Both approaches attempt to convert a hardware choke-point into a product-level screen, but both also multiply the compliance surface and the enforcement cost.
For ASML, the immediate question is whether the next twelve months bring a hard cap on China shipments or merely a continuation of case-by-case licensing. The former would force a strategic recalibration; the latter would extend the current ambiguity and, quite likely, sustain the front-running dynamic that produced this quarter's 109 per cent surge. Either way, the tools already in place will define China's semiconductor capability for the next decade, regardless of what leaves Veldhoven next year.