SpaceX Secures $40 Billion Lease to Fund AI Chip Expansion
The Elon Musk-led company struck a five-year equipment lease with Apollo Global Management, bypassing traditional debt markets as AI infrastructure financing tightens across the industry.
A Five-Year Bet on AI Hardware
SpaceX disclosed a binding commitment for approximately $40 billion in equipment financing on Monday, structured as a lease arrangement with an entity managed by Apollo Global Management. The New York-based private equity firm will purchase AI chips and related server hardware, then lease the equipment back to SpaceX over a five to five-and-a-quarter-year term beginning when each tranche arrives.
The company expects the transaction to close before year-end, with lease payments commencing in the first half of 2027 as Nvidia's next-generation Vera Rubin chips and associated infrastructure reach SpaceX's terrestrial data centres. At Opentechwire, we've tracked the rising cost of AI compute buildouts across the sector, and this deal represents the largest committed GPU financing package disclosed to date.
SpaceX CFO Bret Johnsen characterised the arrangement as a way to diversify funding sources beyond conventional debt instruments. The company is reporting payback periods of under twelve months on its AI infrastructure investments, driven by revenue from Grok, its coding tool Cursor, and cloud compute services.
Revenue Mix Tilts Toward AI
The financing arrives on the heels of a third quarter in which SpaceX's AI segment generated $7.6 billion in revenue, accounting for more than half of the company's $14.6 billion total and outpacing both Starlink satellite internet and launch services combined. Capital expenditures climbed to nearly $20 billion in the quarter, up from $6.9 billion a year earlier, and Johnsen indicated on the 20 October earnings call that fourth-quarter spending could reach $35 billion to $40 billion.
That acceleration reflects the broader arms race in AI compute capacity, where hyperscalers and emerging cloud providers alike are racing to secure the latest generation of accelerators. For SpaceX, the shift also marks a strategic pivot: a company synonymous with reusable rockets and low-Earth-orbit constellations now derives the majority of its revenue from software and cloud infrastructure.
The lease structure allows SpaceX to preserve balance-sheet flexibility while still scaling its GPU footprint. Apollo will hold title to the hardware, and SpaceX will make periodic lease payments over the contract term. That approach keeps the equipment off SpaceX's books as a capital asset and spreads cash outflows across multiple years.
Debt Markets Turn Cautious
The timing of the deal underscores a hardening environment for AI infrastructure financing. Investors have grown increasingly sceptical of companies posting large capital expenditures without near-term profitability, and debt markets have begun to demand higher spreads or turn away issuers altogether.
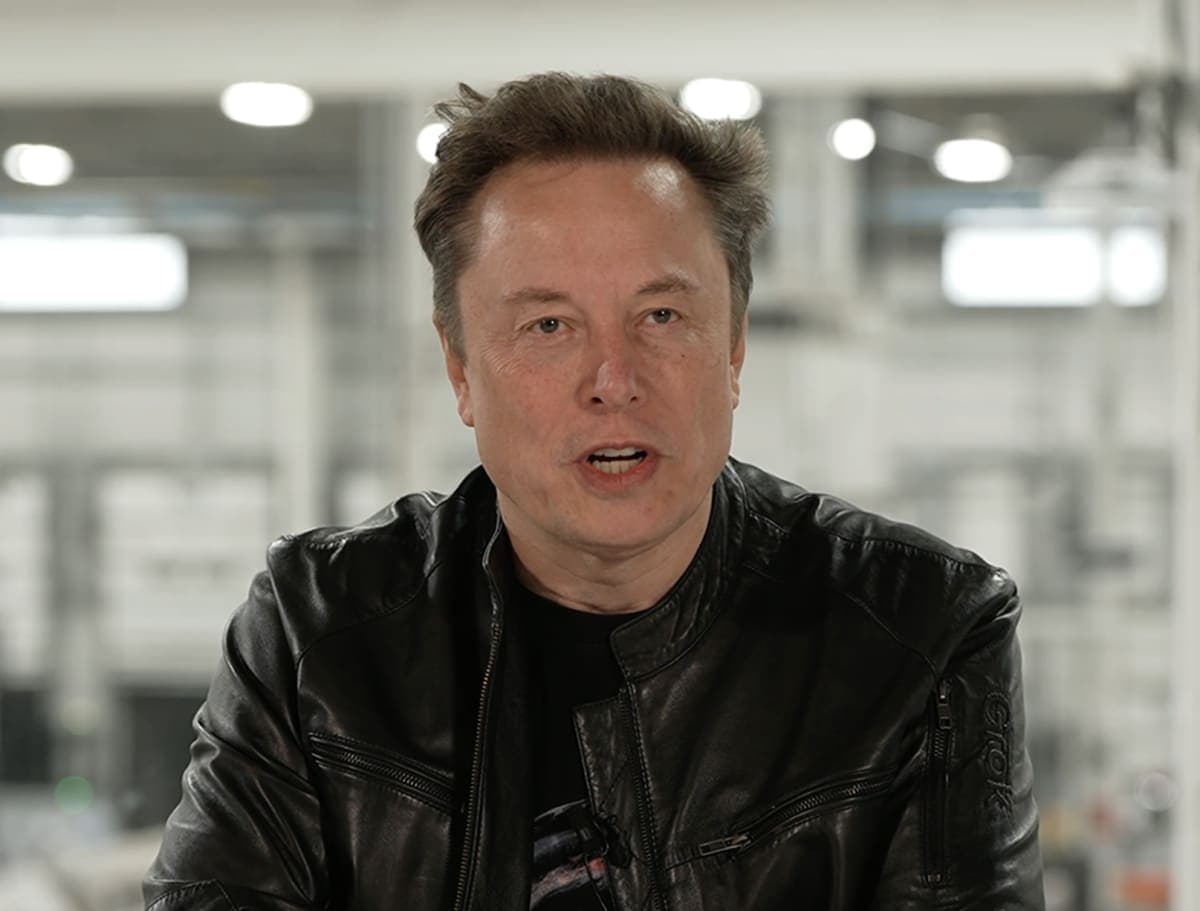
SpaceX, which maintains investment-grade credit metrics and generates steady cash from its launch and Starlink businesses, faced no such obstacles. Elon Musk used the announcement to highlight that contrast, arguing on Sunday that debt markets have effectively closed to companies reliant solely on AI data centre revenue. He singled out the more than 200 neocloud providers built exclusively to lease GPU capacity, predicting a wave of consolidation and failures.
The critique carries weight in a market where several neocloud operators have delayed expansion plans or sought bridge financing at unfavourable terms in recent months. SpaceX's diversified revenue base, its investment-grade rating, and its operational cash flow from legacy businesses provide a cushion that pure-play AI compute firms lack.
Implications for the Neocloud Landscape
Musk's public commentary points to a bifurcation in AI infrastructure finance. Established technology companies with multiple revenue streams and strong credit profiles can still access large-scale capital, whether through debt, equity, or structured leases. Newer entrants without those attributes face tighter scrutiny and, in some cases, a funding drought.
The neocloud sector emerged over the past three years as venture-backed startups raced to aggregate GPU capacity and resell it to AI developers. Many of those firms leased hardware from equipment financiers or relied on vendor credit from chip manufacturers. As interest rates rose and profitability remained elusive, investors began to question the sustainability of that model.
SpaceX's lease, by contrast, leans on the company's broader financial strength rather than speculative growth projections. Apollo is effectively betting on SpaceX's ability to generate sufficient revenue from its AI services to cover lease obligations, backstopped by cash flow from Starlink and launch operations.
What This Signals for Asia-Pacific Players
The deal also has resonance for the Asia-Pacific region, where governments and private consortia are pursuing their own AI compute buildouts. Singapore's national AI infrastructure programme, South Korea's hyperscale data centre incentives, and Japan's semiconductor supply-chain investments all reflect similar ambitions to secure compute capacity in an environment where chip supply remains constrained.
Regional players will be watching whether Apollo's willingness to finance SpaceX's hardware translates into appetite for similar structures in Asia. To date, most large-scale AI infrastructure financing in the region has come from development banks, sovereign wealth funds, or direct government appropriations. Private equity and infrastructure funds have been more cautious, citing regulatory uncertainty and the nascent state of commercial AI markets outside China and a handful of other economies.
If SpaceX's lease performs as expected, it could serve as a template for other diversified technology companies in the region seeking to scale AI infrastructure without tying up equity capital or exhausting credit lines. The five-year lease term aligns with typical hardware refresh cycles, and the structure offers a hedge against obsolescence: SpaceX retains the option to upgrade or swap equipment as newer chip generations arrive, subject to lease terms.
Forward Questions
Several open questions remain. First, the regulatory filing does not disclose the effective interest rate embedded in the lease payments, so it is unclear how the financing cost compares to traditional debt. Second, the phased delivery schedule means SpaceX will be taking on lease obligations incrementally over the coming quarters, complicating quarter-to-quarter cash flow analysis.
Third, the arrangement depends on Nvidia's ability to deliver Vera Rubin chips on schedule. Supply-chain delays or yield issues could push lease commencement dates and disrupt SpaceX's infrastructure rollout. Apollo, for its part, is assuming residual-value risk: if demand for AI accelerators softens or a superior architecture emerges, the equipment Apollo owns could depreciate faster than anticipated.
Finally, the deal raises the stakes for SpaceX's AI business. With lease obligations totalling tens of billions of dollars over five years, the company must sustain rapid revenue growth in Grok, Cursor, and its cloud services to justify the investment. A slowdown in AI workload demand, or increased competition from established cloud providers, could pressure margins and complicate the payback thesis that Johnsen cited.
For now, SpaceX has secured the capital it needs to continue scaling, and Apollo has placed a large bet on the durability of AI compute demand. The outcome will offer a real-world test of whether diversified revenue and investment-grade credit can insulate a company from the financing headwinds buffeting the broader AI infrastructure sector.