Local Government Robotics Funds Face First Wave of Valuation Pressure
District-level investors who poured billions into humanoid robot ventures now confront exit uncertainty and falling IPO appetite as the sector's commercial timeline stretches beyond initial forecasts
The Deal Flow That Wouldn't Stop
He Ziyang's calendar filled with an unusual category of visitor this spring. Four separate municipal delegations arrived at her advisory firm in a single day, each representing a different tier of Chinese local government. Tianjin, Shenzhen, Chengdu, Xiamen - the officials came bearing questions about humanoid robotics companies and how to connect them with capital. He's firm specialises in matching hard-tech ventures with funding sources, a niche that suddenly became critical infrastructure for local economic planners.
The conversations revealed a pattern. Some officials acknowledged they were executing directives without internal expertise in the sector. Others arrived with ambitions that seemed disconnected from their jurisdictions' actual capacity. One delegation from a county-level city of several hundred thousand residents laid out a detailed industrial map - factory space, supplier networks, logistics infrastructure - but admitted they lacked a single anchor robotics firm to justify the ecosystem they had prepared.
At Opentechwire, we've tracked similar dynamics across Southeast Asian tech hubs, where government-led venture funds often chase sectors before developing thesis clarity. The Chinese robotics wave stands out for its scale and the speed at which capital commitments have outpaced commercial validation.
State Capital Moves to Centre Stage
Data from ITjuzi show the embodied intelligence sector recorded over 300 financing transactions in the first half of 2026, a 137 per cent increase year-on-year. Disclosed funding reached RMB 93.5 billion (USD 14 billion). State-backed institutions participated in 42 per cent of large rounds, according to the research firm. By late 2025, municipal funds in Shanghai, Shenzhen, Hangzhou, Suzhou, Hefei, Wuxi, Ningbo and Nanjing had entered the sector with dedicated robotics vehicles.
Liu Kaijie, an investor at an established hard-tech fund, noted that leading robotics companies were closing rounds of RMB 1 billion (USD 150.1 million) or more. The funding environment, he said, had become predictable. One state-fund investor described the strategy in stark terms: back either a technology leader mimicking global innovation, or align with national industrial policy. Both paths offered apparent safety.
The model borrowed from Hefei's earlier success in semiconductor and electric vehicle investments, where municipal capital catalysed private follow-on funding and attracted manufacturing operations. Robotics investors moved from complete humanoid systems to upstream components - motors, reduction gears, sensors - and then to foundational models for robotic control. State capital followed each shift.
September's Confidence Break
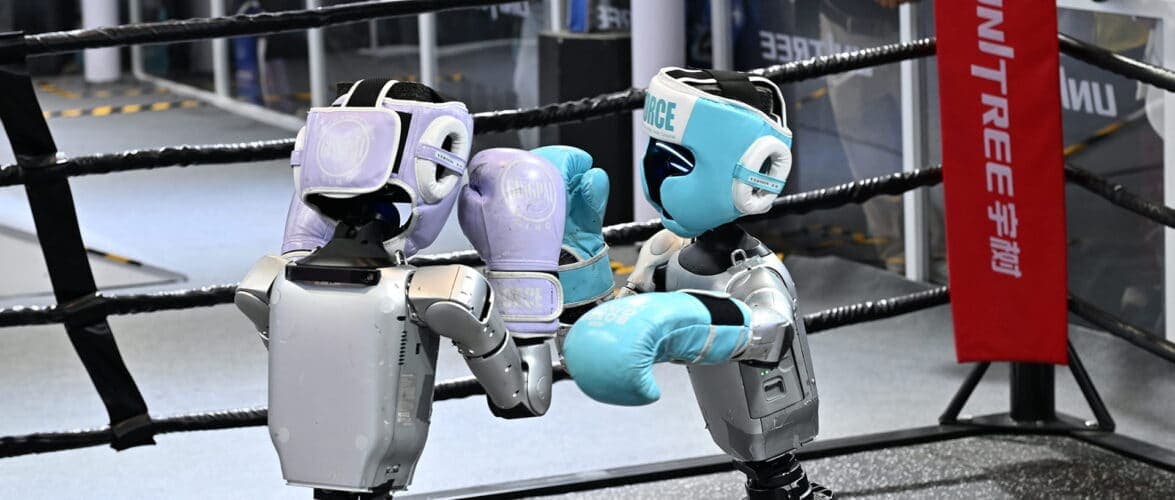
The sector's trajectory changed in autumn. Unitree Robotics, which had shipped more than 5,000 humanoid units in the first half of 2026 and ranked second globally by volume according to industry data, lost half its market capitalisation after listing on the Shanghai Stock Exchange's Star Market. Mech-Mind Robotics' founder published a public critique of industry practices on WeChat. Hong Kong adjusted its Chapter 18C listing rules for specialist technology companies earlier in the year, tightening requirements.
Multiple investors told Opentechwire that financing conditions would tighten sharply after November 2026. Companies still held cash from previous rounds, but new capital would arrive at lower valuations. More concerning for state-backed investors: exit routes were narrowing. Second- and third-tier robotics firms faced diminished IPO prospects, threatening both the financial returns local funds expected and the industrial clustering they were mandated to achieve.
A district-level investor in Shenzhen described the technical uncertainty. The sector iterates every three months, with six-month cycles capable of overturning prior assumptions. Commercial timelines remain opaque. Huang Jinping, founding partner and chairman of Winreal Investment, warned that robotics companies require years to mature and that an industry contraction could leave few viable players.
The Horse Bone Strategy
Local officials have adopted a framework drawn from a Warring States-era parable. A ruler seeking exceptional horses struggled to attract sellers until a minister purchased the bones of a dead horse at a conspicuous price, signalling the ruler's seriousness. Within a year, three living horses arrived. The logic: demonstrating commitment attracts opportunity.
Cities pursuing "new quality productive forces" under the 15th five-year plan face constrained options. Quantum computing, commercial spaceflight and controlled fusion require national-scale research infrastructure and concentrated scientific talent. Few municipalities can host them. Robotics offers modularity. Assembly, component manufacturing, software development and data operations can distribute across locations. A city need not secure a complete humanoid robot manufacturer; a joint motor supplier or dexterous hand producer satisfies near-term targets, generates future tax revenue and justifies broader sectoral ambitions.
Districts receive differentiated mandates to avoid redundant competition, according to investor accounts. One focuses on key components, another on complete systems and AI developers, a third on end-effectors. Companies have adapted fundraising strategies accordingly, studying which industrial assets accompany available capital. They divide operations to match local needs, placing headquarters, R&D centres, production lines and data centres in separate jurisdictions.
One investor described the practice: if a locality lacks complete machines, pitch the robot itself; if it wants components, emphasise motors and gears; if it requires physical presence, build a data centre. For some local state investors, the priority is documenting that investment promotion targets have been met. Hard-tech investments permit longer timelines and greater tolerance for early-stage losses, provided officials can demonstrate due diligence.
The investor outlined a familiar sequence: companies identify gaps in a city's sectoral portfolio, sign agreements to establish a base, secure factory premises, arrange pilot orders with industrial partners, issue scheduled press releases and host official site visits. The documentation must construct a coherent narrative before commercial results materialise. Over time, a company with minimal revenue can appear in municipal reports as a key enterprise in the local robotics supply chain.
Three Categories of State Capital
China's state investment apparatus is not monolithic. Funding sources, performance metrics, risk appetite and investment styles vary across institutional types and administrative levels.
The first category serves parent conglomerates' industrial needs. Investment platforms under centrally administered state-owned enterprises - CITIC-affiliated funds, CRRC Capital - deploy earmarked funding to address supply chain gaps or open adjacent business opportunities. CRRC's transformation and upgrading fund invested in AI² Robotics, describing the fit as a natural ecosystem alignment. CRRC operates advanced manufacturing facilities and seeks to understand whether embodied intelligence can integrate into existing production lines. Individual investment returns matter less than strategic positioning.
The second category targets local economic development. District- and county-level state platforms and industrial funds have been the most active participants in the robotics boom. Their obligation to preserve and increase state asset value makes them cautious. They typically prefer later-stage companies with valuations in the tens of billions of RMB, closer to private equity territory. Wu Jianyu, who heads a district-level investment promotion centre in a second-tier city, explained that the primary measures are whether a company will locate R&D centres, production lines and support teams locally, and whether it can attract upstream and downstream partners to form a cluster. The company's short-term valuation and listing timeline rank lower.
The third category comprises commercially oriented state funds whose primary mandate is financial return. Shenzhen and Shanghai have piloted reforms that classify funds by objective, allowing some to be assessed on investment performance rather than local business attraction. These funds do not require companies to build local factories, relaxing residency requirements in favour of growth potential and exit returns. Examples include TopoScend Capital under Shenzhen Investment Holdings, an AI industry fund managed by SCGC, and subfunds under Shanghai State-owned Capital Investment. Such institutions have backed leading embodied intelligence companies including Astribot, Agibot and X Square Robot.
Performance Measurement Looms
The question facing district-level investors is whether the robotics sector will mature fast enough to justify the capital committed. Companies that raised at high valuations in 2025 and early 2026 now confront a market less willing to support follow-on rounds at comparable terms. For state-backed investors whose mandates emphasise local industrial development over pure financial return, the calculus is more complex. A company that relocates R&D operations or scales back manufacturing plans undermines the clustering logic that justified the initial investment.
Regional competition intensifies the pressure. Officials compete for recognition within government hierarchies and for market positioning. A municipality that secures a prominent robotics firm gains leverage in negotiations with component suppliers and systems integrators. One that invests heavily but fails to attract sustained operations risks both financial loss and reputational damage within the administrative system.
The sector's technical trajectory remains uncertain. Humanoid robots have demonstrated capability improvements, but commercial applications at scale remain confined to controlled environments - warehouses, inspection tasks, limited manufacturing roles. Consumer markets have yet to materialise in meaningful volume. The timeline to profitability for most robotics ventures stretches years into the future, a horizon that tests the patience of state investors facing annual performance reviews.
The Cluster That Isn't
One investor described the current landscape with scepticism. Multiple localities believe they have secured the most critical piece of the robotics value chain. In reality, they are collectively supporting an industry whose centre of gravity has yet to emerge. The metaphor: everyone is carrying a sedan chair, but no-one wants to be the first to ask whether anyone is sitting inside.
The comparison to earlier investment cycles is instructive. Consumer internet, entertainment and e-commerce booms were driven primarily by commercial venture capital. State-backed investors participated but did not dominate. Hard-tech sectors - semiconductors, robotics, advanced materials - present different economics. Capital requirements are higher, commercialisation timelines longer, and strategic considerations more acute. Commercial funds alone struggle to sustain the sector, creating space for state capital to play a larger role.
That shift brings advantages: patient capital, willingness to fund infrastructure, alignment with industrial policy. It also introduces risks. Investment decisions influenced by administrative targets rather than commercial fundamentals can misallocate resources. Companies optimise for government relations rather than product-market fit. Clusters form on paper but lack the organic linkages - talent mobility, supply chain density, customer proximity - that characterise successful industrial ecosystems.
The coming months will test whether the robotics investment wave represents a durable shift in China's industrial structure or a cycle of enthusiasm that outpaced underlying demand. For the local officials who filled He Ziyang's calendar this spring, the stakes are concrete: budgets committed, agreements signed, performance targets set. The sector's commercial success will determine whether those commitments generate the industrial transformation they were designed to achieve, or whether they become cautionary examples in the next wave of policy experimentation.