Google Bets Asia Will Lead Cloud Revenue Growth as AI Demand Surges
The search giant's regional AI chief sees enterprises racing to deploy generative tools at a pace that dwarfs the cloud migration wave, driven by cost pressures and competitive necessity.
Adoption Velocity Defies Historical Patterns
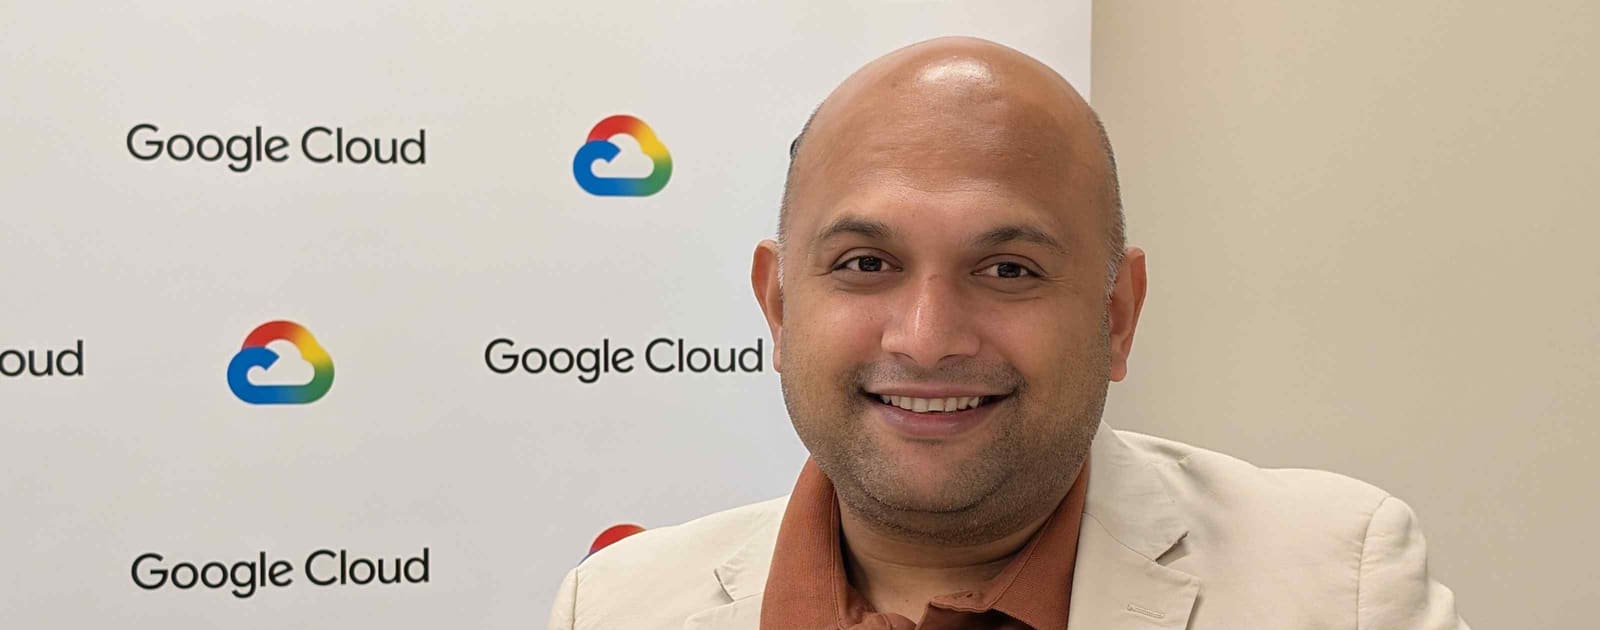
Generative AI is embedding itself into Asian enterprise workflows at a speed that has caught even platform vendors off guard. Harsha Konduri, managing director for Google AI across Asia-Pacific and Japan, noted in Tokyo that the technology reached widespread deployment in roughly two years, a fraction of the decade-plus that cloud computing required to achieve similar penetration. That compression reflects both the immediacy of cost pressures facing regional firms and the lower barriers to experimentation that large language models and pre-trained APIs afford.
At Opentechwire, we have tracked adoption curves across Seoul, Singapore, and Bangalore for the past eighteen months, and the pattern is consistent: proof-of-concept cycles that once spanned quarters now close in weeks, and budget sign-offs that required board approval are increasingly delegated to division heads. The velocity is less about hype and more about arithmetic. When a customer-service team in Jakarta can halve response times with a fine-tuned chatbot, or a logistics operator in Bangkok can shave five per cent off route-planning costs with an inference endpoint, the return-on-investment case writes itself.
Platform Strategy Shifts Toward Governance and Cost Control
Google's response to this demand surge centres on what Konduri described as a platform approach, emphasising security, governance, and cost-management tooling rather than raw model performance alone. That positioning is deliberate. Enterprises in the region have learned hard lessons from earlier cloud migrations: vendor lock-in, runaway egress fees, and compliance gaps that surfaced only after production deployments. The second wave of infrastructure buyers is more cautious, and Google is tailoring its pitch accordingly.
The emphasis on governance is particularly salient in markets where data-residency rules and sector-specific regulations are tightening. Financial institutions in Singapore, healthcare providers in Seoul, and e-commerce platforms in Mumbai all face overlapping but distinct compliance frameworks, and none can afford the reputational or regulatory cost of a data breach tied to an AI system. By bundling observability, audit logging, and policy enforcement into its cloud AI stack, Google is effectively commoditising the compliance layer, turning what was once a bespoke integration challenge into a checkbox feature.
Cost management, meanwhile, addresses a pain point that has only intensified as generative workloads scale. Inference latency and token throughput translate directly into compute spend, and enterprises that ran pilot projects on generous free tiers are now confronting monthly bills that can rival their legacy IT budgets. Tools that surface per-query costs, enable dynamic model routing, or allow hybrid on-premises and cloud deployments are no longer nice-to-haves; they are table stakes in any serious enterprise conversation.
Regional Dynamics and the Margin Imperative
The urgency driving AI adoption in Asia differs in texture from what we observe in North America or Europe. Margins in many regional industries are thinner, labour arbitrage is less reliable as wage growth accelerates, and competition is often more fragmented. A manufacturer in Vietnam competing with peers in Thailand and Indonesia cannot afford a two-year deliberation on whether to automate quality inspection; delay is itself a strategic risk.
Konduri's focus on cost-effectiveness as a primary motivator aligns with this reality. Enterprises are not chasing moonshots or research breakthroughs. They are deploying AI to defend existing margins, to maintain service levels without proportional headcount increases, and to extract incremental efficiencies from supply chains that are already highly optimised. The use cases are prosaic but high-volume: invoice processing, inventory forecasting, call transcription, content moderation, fraud detection. Individually modest, collectively they represent a substantial and recurring revenue opportunity for cloud providers.
Competitive Landscape and the Race for Integration Depth
Google enters this growth phase from a position that is strong in some dimensions and contested in others. Its AI research pedigree and the breadth of its model portfolio, spanning Gemini and vertical-specific offerings, give it credibility with technical buyers. However, it trails Amazon Web Services in raw infrastructure footprint across the region, and Microsoft has leveraged its enterprise software incumbency to bundle AI features into Office 365 and Dynamics deployments with minimal friction.
The battle will be won or lost not on model benchmarks but on integration depth. Enterprises want AI capabilities that slot into existing SAP environments, that interoperate with Salesforce instances, that respect the identity and access-management policies already in place. Google's platform strategy is an acknowledgement of this reality: the vendor that reduces the activation energy required to move from pilot to production will capture disproportionate share.
We are also seeing early signs of a bifurcated market. Tier-one multinationals and well-capitalised unicorns have the resources to run multi-cloud strategies, cherry-picking best-of-breed services from AWS, Google, and Azure. Smaller firms and mid-market enterprises, by contrast, gravitate toward single-vendor platforms that bundle infrastructure, models, and tooling, accepting some loss of flexibility in exchange for simpler procurement and support. Google's emphasis on governance and cost control is a play for both segments, but the bundled-platform narrative resonates more strongly with the latter.
The Talent Bottleneck and Its Implications for Vendor Strategy
One constraint that consistently surfaces in our conversations with regional CTOs is the scarcity of AI engineering talent. Universities in India, China, and Southeast Asia are producing computer science graduates at scale, but the subset with hands-on experience fine-tuning models, optimising inference pipelines, or debugging hallucination issues in production remains thin. This shortage has strategic implications for vendors.
Platforms that lower the skill floor, offering managed services, AutoML workflows, and pre-built connectors, become more attractive when internal expertise is scarce. Google's bet on platform features rather than raw infrastructure is partly a response to this dynamic. If a retailer in Manila can deploy a recommendation engine via a GUI and a handful of API calls, rather than hiring a team of ML engineers, the addressable market expands significantly.
That said, the talent gap also creates risk. Enterprises that lack deep AI literacy may deploy systems without adequate testing, monitoring, or fallback mechanisms, leading to operational failures that erode confidence in the technology. Vendors that invest in education, offer robust support tiers, and build guardrails into their platforms will likely see better retention and fewer high-profile customer churn events.
Forward Outlook and the Margin-Compression Cycle
The rapid adoption Konduri describes is unlikely to plateau in the near term. Competitive pressure, regulatory nudges toward digitalisation, and the falling cost of inference will sustain demand. However, the nature of that demand will evolve. Early adopters have picked the low-hanging fruit, automating tasks with clear ROI and minimal integration complexity. The next phase will involve more complex workflows, multi-modal data, and tighter coupling with legacy systems, all of which raise the bar for vendor capabilities.
There is also a looming margin-compression cycle. As AI capabilities diffuse and become table stakes, the competitive advantage any single deployment confers will diminish. A chatbot that differentiates a brand today will be unremarkable in eighteen months. Enterprises will need to run faster to stay in place, and vendors will need to offer not just better models but better economics, better tooling, and better integration.
Google's platform strategy positions it to navigate this shift, but execution will matter. The vendor that can deliver consistent, predictable costs; that can simplify compliance across heterogeneous regulatory regimes; and that can reduce the time from idea to production deployment will capture the lion's share of what is shaping up to be a multi-year infrastructure upgrade cycle across Asia. The perception gap Konduri highlighted is closing, but the revenue opportunity it represents is only beginning to materialise.