China's Generative AI Users Surpass 700 Million as Adoption Accelerates
More than half the country's population now uses generative AI tools, marking a 16 per cent surge in six months and setting a new benchmark for consumer AI adoption at scale.
Record Penetration Across the World's Largest Internet Market
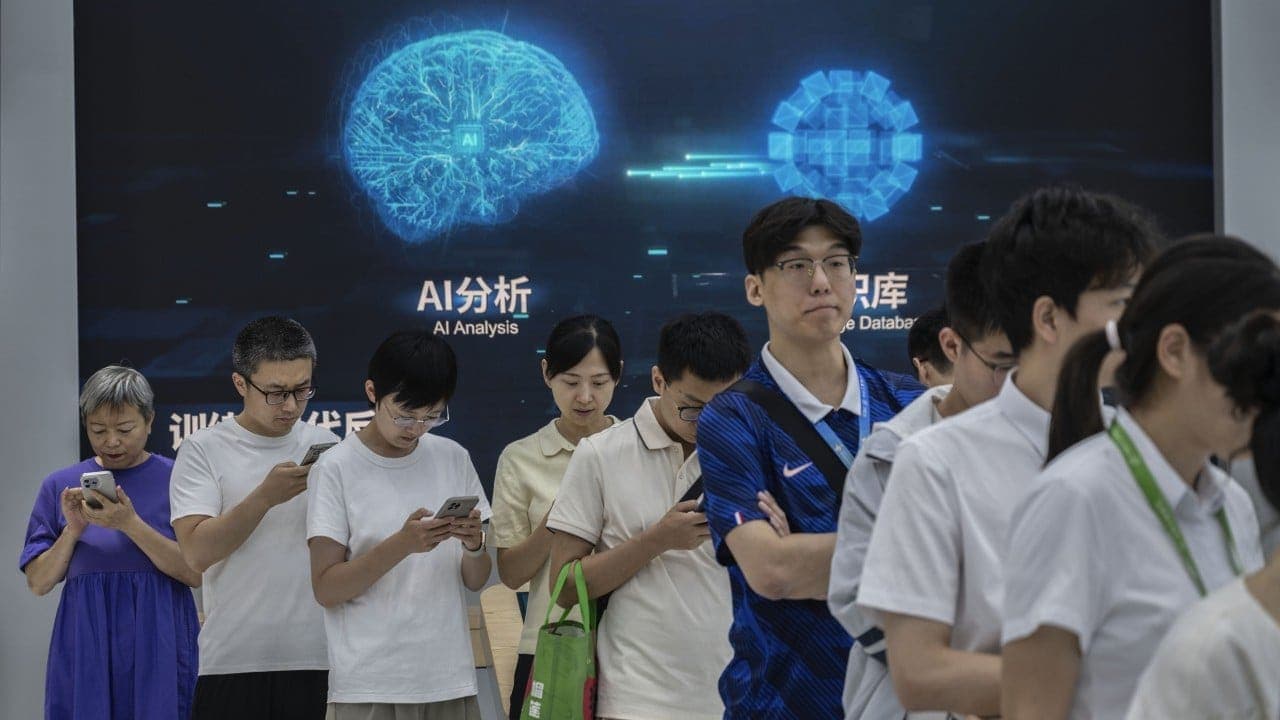
By the end of June 2026, more than 700 million people in China were actively using generative AI tools, according to data released by the China Internet Network Information Centre. That figure represents a penetration rate exceeding 50 per cent of the population, a milestone no other major economy has yet approached. At Opentechwire, we've tracked the rise of consumer AI platforms across Asia, but the speed at which mainland users have integrated question-and-answer systems, content generators, and multimodal assistants into daily workflows stands apart.
The user base expanded by 16 per cent in the first half of 2026 alone. Six months earlier, at the close of 2025, the country counted 602 million generative AI users and a penetration rate of 42.8 per cent. The seven-percentage-point jump in penetration within two quarters signals that adoption is no longer confined to early adopters or tech-adjacent cohorts; it has moved into mainstream consumer behaviour.
What Drives the Numbers
Question-and-answer applications remain the dominant entry point. Platforms such as those operated by Baidu, Alibaba, and a constellation of smaller firms have embedded generative models into search engines, messaging apps, and productivity suites. Users prompt these systems for everything from trip itineraries to legal contract summaries, creating a feedback loop that improves model quality and reinforces habit formation.
Content creation tools, particularly those generating text, images, and short video scripts, have also gained traction among small businesses and individual creators. The lower barrier to producing marketing copy or social media visuals has democratised access to design and editorial workflows that previously required specialist skills or outsourced labour. In tier-two and tier-three cities, where freelance content creation is a growing income source, generative AI has become infrastructure rather than novelty.
Mobile-first distribution plays a structural role. Unlike markets where desktop remains a significant interface for productivity software, China's internet users overwhelmingly access services via smartphone. Generative AI features ship as native components of super-apps, reducing the friction of discovery and onboarding. A user opening a payment app or a ride-hailing platform may encounter an AI assistant without ever downloading a standalone tool.
Implications for Model Developers and Compute Capacity
Serving 700 million active users places sustained demand on inference infrastructure. Model providers must balance latency, cost per query, and the computational overhead of increasingly multimodal requests. Edge deployment, where lighter models run on-device or at regional data centres, has become a common strategy to manage load and comply with data-residency requirements. The scale also creates an incentive to optimise models for efficiency rather than raw capability, a trade-off that shapes the product roadmap of every major AI lab in the country.
The user base offers a training data advantage. Prompts, corrections, and user interactions generate a continuous stream of feedback that can fine-tune models for local language nuances, regional dialects, and domain-specific terminology. This flywheel effect, where adoption fuels model improvement and improved models drive further adoption, is difficult for competitors outside the ecosystem to replicate.
At the same time, the concentration of users within a single regulatory jurisdiction exposes the ecosystem to policy shifts. Content moderation, data-retention mandates, and restrictions on cross-border data flows all impose costs that model operators must internalise. The regulatory environment remains a variable that can accelerate or constrain the trajectory of adoption.
Regional Context and Comparative Scale
China's 700 million generative AI users now exceed the combined internet populations of the United States and the European Union. The penetration rate also surpasses early estimates for other large Asian markets; India's generative AI user base, though growing rapidly, is estimated to be in the low hundreds of millions, while Southeast Asia's fragmented language and connectivity landscape has slowed uniform adoption.
The scale creates network effects that extend beyond borders. Chinese model developers are exporting inference APIs, pre-trained models, and application frameworks to markets in Latin America, the Middle East, and parts of Africa, often at price points that undercut Western providers. The domestic user base serves as proof of concept and as a subsidy mechanism; revenue from hundreds of millions of paying or ad-supported users in China can fund international expansion.
For hardware suppliers, the user growth translates into sustained demand for GPUs, custom accelerators, and networking equipment. Domestic chip designers, constrained by export controls on leading-edge lithography, have focused on optimising architectures for inference rather than training, a pragmatic response to both market demand and supply-chain realities.
Questions of Sustainability and Market Saturation
A penetration rate above 50 per cent raises questions about the durability of growth. The next hundred million users will likely come from older demographics, rural areas with lower digital literacy, and use cases that require more onboarding or behaviour change. Conversion rates in these segments tend to be slower, and retention may prove more volatile.
Monetisation remains uneven. While premium subscription tiers and enterprise licensing generate revenue for leading platforms, a substantial portion of the user base accesses free or ad-supported services. The unit economics of serving a query, particularly for multimodal or long-context requests, can exceed the revenue captured from that user. Platforms are experimenting with tiered access, token limits, and bundled services to improve margins without triggering churn.
The competitive landscape is also consolidating. Smaller model providers that cannot achieve the scale or capital efficiency of the top three or four platforms face pressure to exit or merge. This dynamic may reduce diversity in model architectures and product approaches, even as the aggregate user base continues to grow.
What This Means for the Global AI Landscape
China's generative AI adoption curve now serves as a reference point for policymakers, investors, and product teams worldwide. The speed of penetration suggests that consumer AI, when integrated into existing digital habits rather than positioned as a standalone category, can achieve mass-market scale within a few quarters. It also underscores the importance of mobile infrastructure, localised content moderation, and regulatory clarity in enabling that scale.
For venture capital and corporate strategy teams tracking the region, the 700 million figure is both a market size and a competitive moat. Any new entrant must contend with incumbents that have years of user data, established distribution, and the operational experience of serving hundreds of millions of concurrent queries. The barriers to entry have risen in proportion to the user base.
The adoption milestone also highlights the divergence in AI product strategy between China and Western markets. While much of the conversation in Silicon Valley and European tech hubs centres on frontier models, reasoning capabilities, and alignment research, the focus in China has tilted towards deployment at scale, cost efficiency, and integration into commerce and content workflows. Both approaches will shape the technology's evolution, but they reflect different assumptions about where value is captured and how quickly.
At Opentechwire, we expect the next phase of growth to hinge less on user acquisition and more on depth of engagement: how many queries per user, how many workflows replaced, and how much revenue per interaction. The headline figure of 700 million is significant, but the composition of that usage, and the infrastructure required to sustain it, will define the next chapter of generative AI in the world's largest internet market.